Jos metallurgical centre showed auditors no insurance policy for N16.62bn of assets; the 2023 Appropriation Act had given it N576,675 for premiums
The Auditor-General's 2024 non-compliance report raises eight queries on the National Metallurgical Development Centre in Jos for 2023. Assets valued at N16.62 billion had no insurance policy the auditors could see; the 2023 Appropriation Act, which Vero Record checked line by line, gave the centre N576,675 for premiums. The Act also matches the budget figures behind a N256.91 million overspending query, 94.8 per cent of which is salaries the centre says are paid centrally, not by it. A N300.06 million "Peculiar Allowance" paid through 2023 had no approval from the wages commission, the auditors say.
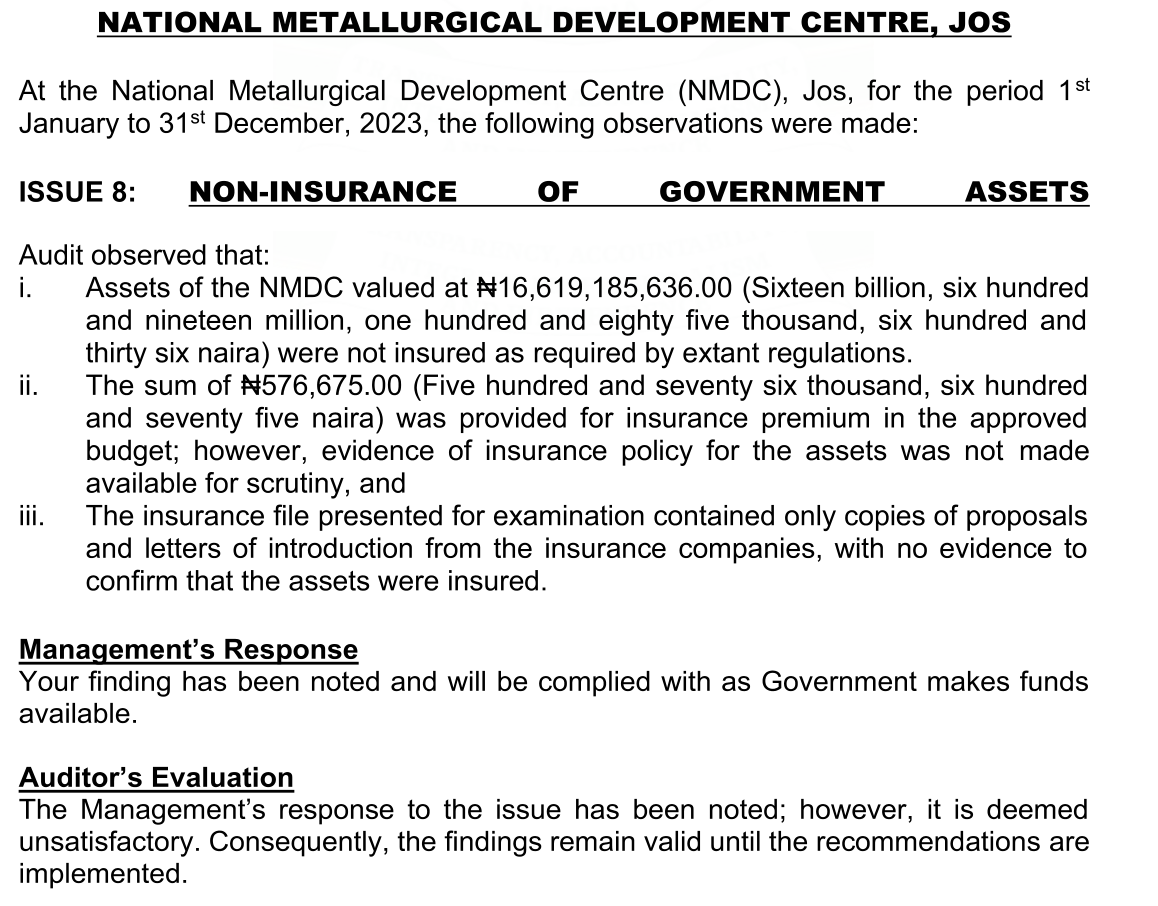
The National Metallurgical Development Centre in Jos, a federal research body under the steel ministry, held assets valued at N16,619,185,636.00 in 2023 and could show the Auditor-General no policy insuring any of them. The insurance file the auditors were given "contained only copies of proposals and letters of introduction from the insurance companies". The 2023 Appropriation Act gave the centre N576,675 for insurance premium, out of a total budget of N1,036,787,527. That is one naira of premium for every N28,819 of assets the auditors counted. The centre's reply was one sentence: "Your finding has been noted and will be complied with as Government makes funds available."
The query is the last of eight on the centre in the Auditor-General's 2024 Annual Report on Non-compliance, Volume II, on printed pages 702 to 713, covering 1 January to 31 December 2023. Seven of the queries are about money paid or not remitted and add up to N687,512,202.76; the eighth, on insurance, is about the value of assets and is not a payment. Each query sets out the rule, what the auditors observed, the management's response, the auditor's evaluation and recommendations to the Director-General, among them that he account for the sum to the Public Accounts Committees of the National Assembly. An audit query is not a finding of wrongdoing. Where the report says there was "no evidence" or that a record was "not made available", it means the auditors were not shown it. The centre answered all eight queries; the auditors kept every finding open. Vero Record set the queries against the centre's lines in the 2023 Appropriation Act, as published by the Budget Office of the Federation, and in the 2026 Act.
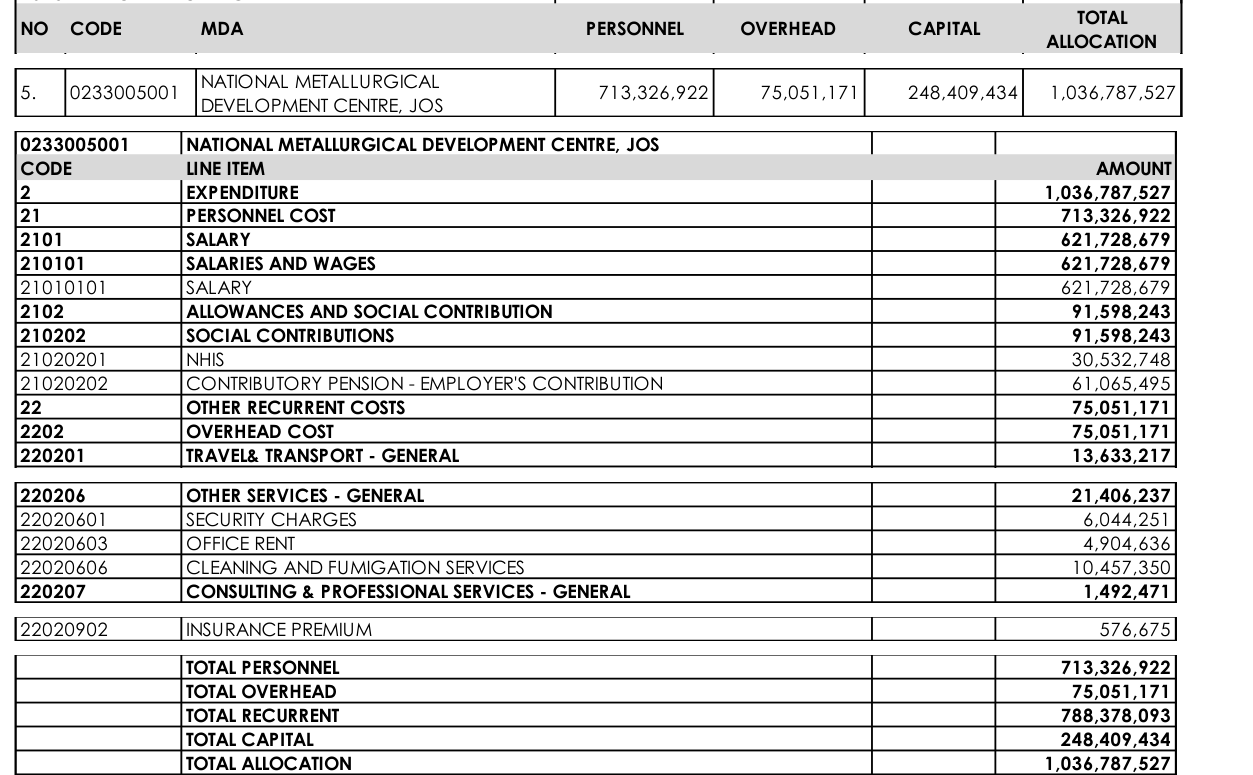
The Act bears out every budget figure the auditors cite. The summary of the Ministry of Mines and Steel Development gives the centre N713,326,922 for personnel, N75,051,171 for overheads and N248,409,434 for capital, which add to N1,036,787,527, the total the report quotes. The centre's detailed overhead schedule carries line 22020902, "Insurance premium", at N576,675, the sum the report says was "provided for insurance premium in the approved budget". The premium vote is 0.0035 per cent of the N16.62 billion asset value. On this point the Act supports the centre's answer as far as it goes: the National Assembly voted very little for premiums. The report does not say how the assets were valued, which assets the figure covers, or whether any of the N576,675 was spent.
The 2026 Appropriation Act raises the centre's insurance premium line to N10,000,000, 17.3 times the 2023 vote, within a total budget of N1,828,093,241: N910,938,054 for personnel, N188,617,768 for overheads and N728,537,419 for capital. Nothing in the records obtained shows whether the centre has since insured its assets.
A second query, for N256,911,576.00, sets the centre's 2023 spending against the Act line by line. The auditors took four subheads with a combined budget of N749,858,847 and found actual spending on them of N1,006,770,423, drawn from the statement comparing budget and actual figures in the centre's 2023 audited financial statements. The three overhead budgets in their table match the Act exactly: N13,633,217 for travel and transport, N21,406,237 for other services and N1,492,471 for consulting and professional services. Against those, the centre spent N23,040,013 on travel, 1.69 times the vote, N22,748,011 on other services and N4,120,000 on consulting, 2.76 times the vote. The auditors found "no evidence of supplementary appropriation or approved virement".
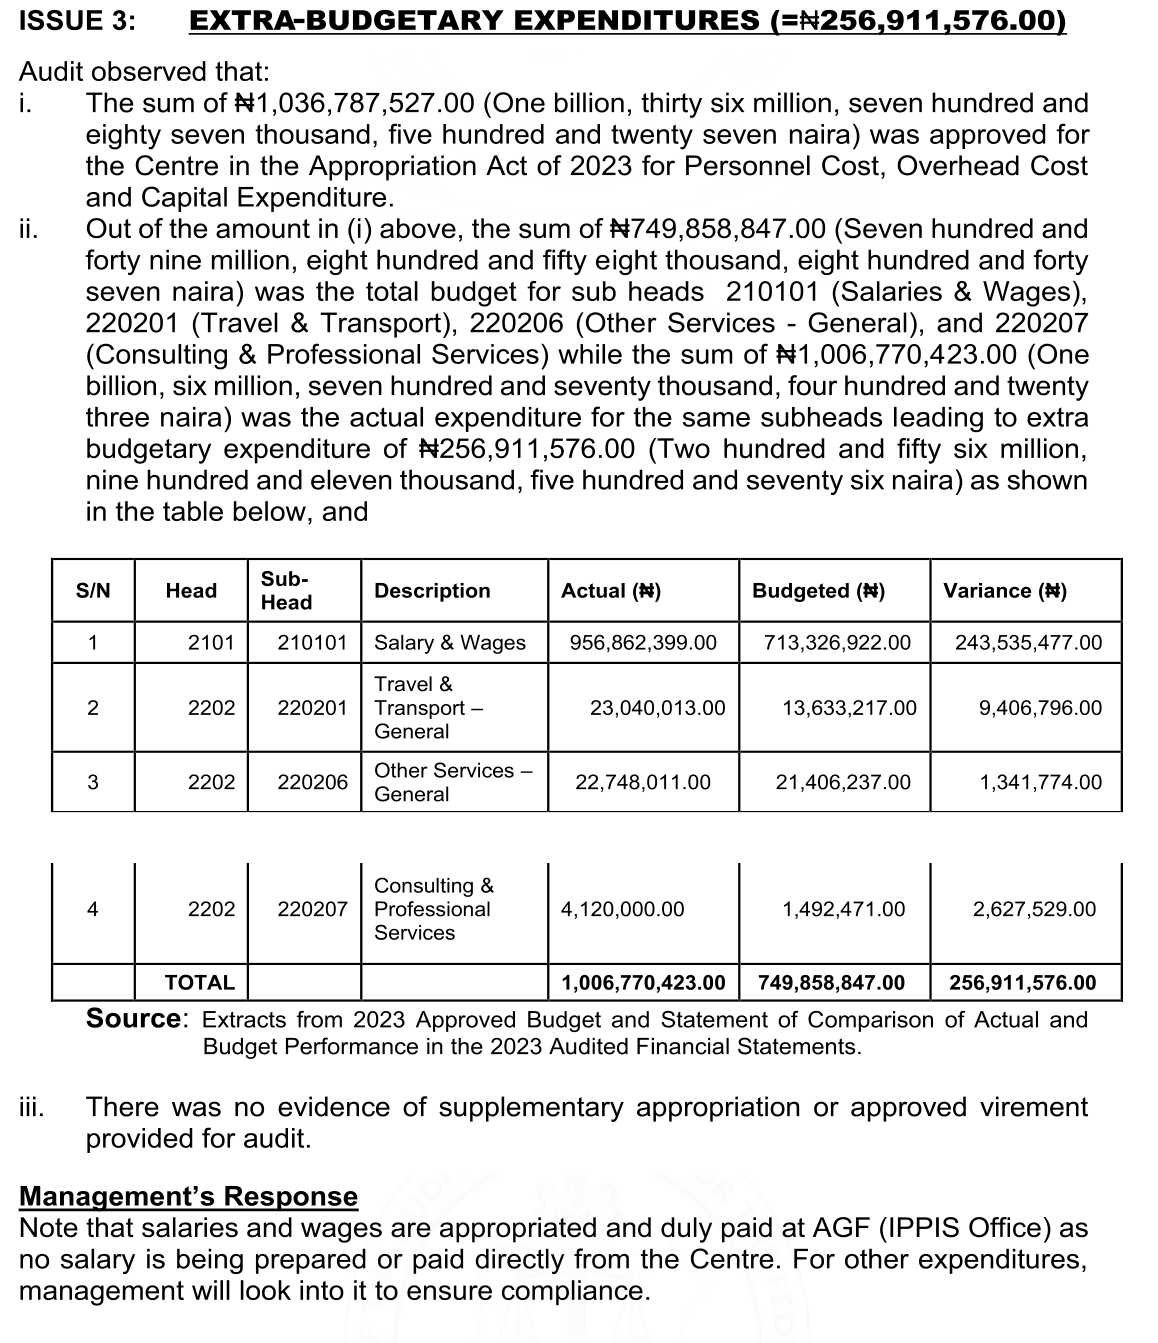
Most of that gap is salaries, and on salaries the centre has an answer, which the auditors judged unsatisfactory without saying why. Of the N256,911,576, N243,535,477, or 94.8 per cent, is the salaries line: N956,862,399 spent against N713,326,922 budgeted. The centre replied that "salaries and wages are appropriated and duly paid at AGF (IPPIS Office) as no salary is being prepared or paid directly from the Centre", and that it would look into the other items, whose overrun comes to N13,376,099. The salary budget the auditors use is itself the Act's whole personnel vote, which also covers N30,532,748 for health insurance and N61,065,495 for the employer's pension contribution; the Act's own salaries and wages line, 210101, is N621,728,679. The report does not say which of these its N956,862,399 corresponds to.
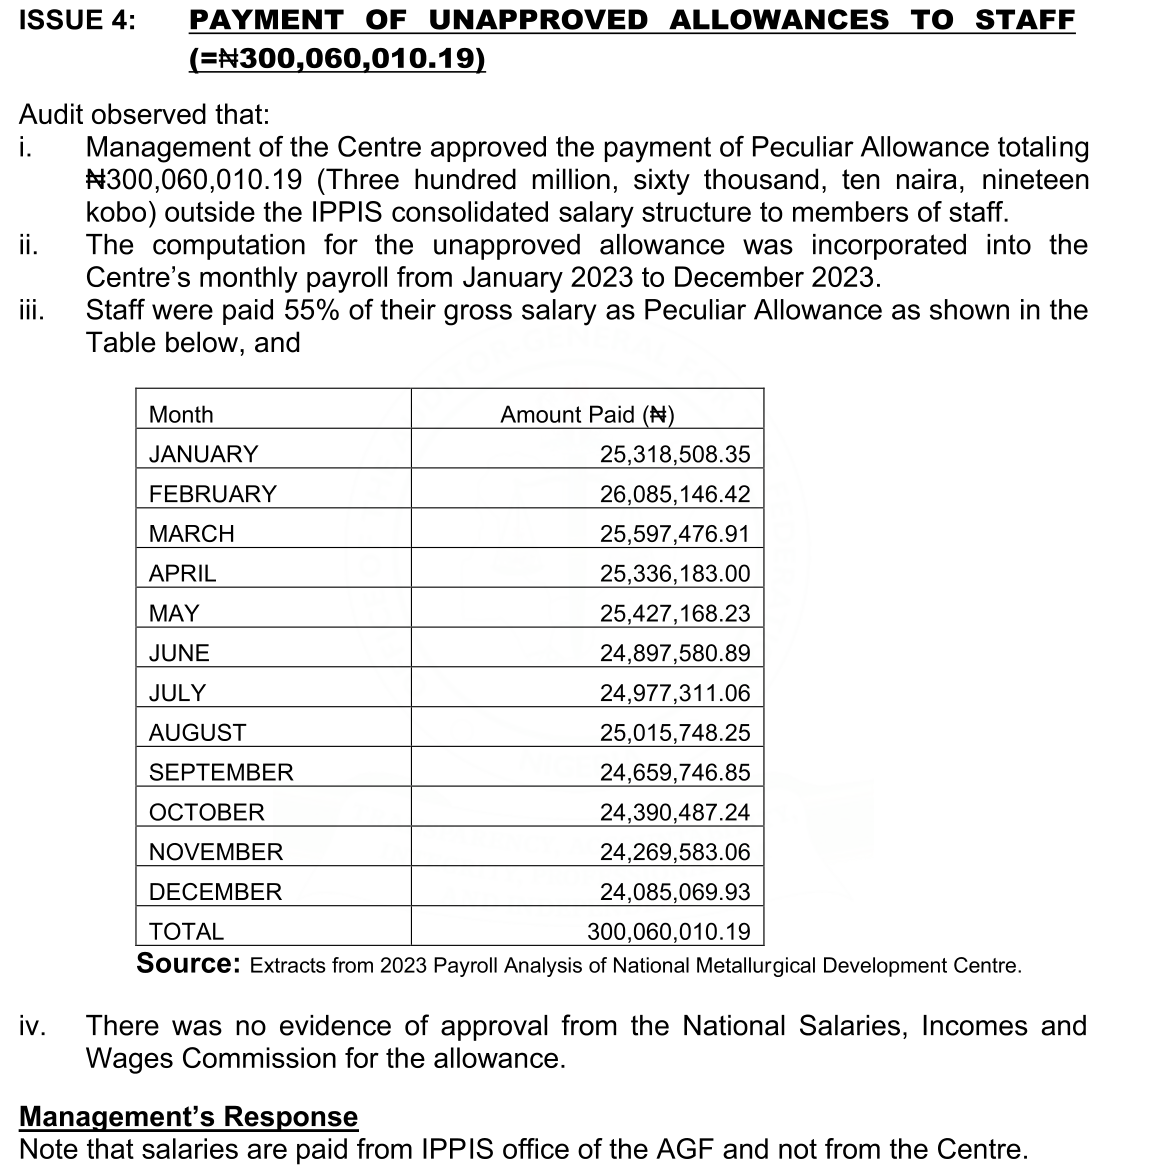
The largest payment query is N300,060,010.19 of "Peculiar Allowance". The auditors say the centre's management approved the allowance "outside the IPPIS consolidated salary structure", that it was built into the centre's monthly payroll from January to December 2023, and that staff were paid 55 per cent of their gross salary under it. Their table, taken from the centre's 2023 payroll analysis, runs from N26,085,146.42 in February to N24,085,069.93 in December; the twelve months re-add to N300,060,010.19, an average of N25,005,000.85 a month. The auditors found no evidence of approval from the National Salaries, Incomes and Wages Commission. The centre's reply, in full: "Note that salaries are paid from IPPIS office of the AGF and not from the Centre." The report does not reconcile the two accounts.
The 2023 Act gives the centre's personnel vote no line for allowances. It lists salary at N621,728,679 and two social contributions, health insurance and pension, at N91,598,243. The 2026 Act's personnel vote of N910,938,054 does include a line for "Regular allowances", at N94,866,406. Neither Act names a peculiar allowance, and the report does not say whether the 2023 allowance is part of the N956,862,399 counted as salaries.
One query concerns the centre's own plant. The auditors say N23,778,000 was paid as 30 per cent mobilisation on two contracts worth N60,000,000 and N19,260,000, N79,260,000 in all, for research equipment and for the "reactivation of two (2) electric arc furnaces with on-the-job training, operation and maintenance", both awarded on 2 August 2023, without an advance payment guarantee. For the furnace contract, a performance bond was produced with cover from 27 June to 26 September 2024; the mobilisation fee had been paid on 3 October 2023, 268 days before the cover began. The centre replied that the contractor "is well known to the Centre, having no previous record of defaulting" and was paid so as not to delay the work, and that "a performance bond was later received". The 2023 Act's project list for the centre has no line that names furnaces, and the report does not say which line paid.
The other queries are smaller. N54,769,299.65 in fourteen payments was charged to the 2023 budget to settle duty tour allowances and air tickets left over from 2022, and included contracts with no budgetary provision; the centre said these were running costs it could not pay in the year they fell due "due to lack of fund", and that the capital budget year had been extended. N50,516,499.65 in six payments for equipment, construction works and services was paid "without evidence of pre-payment audit such as Internal Audit stamps"; the centre said any unstamped voucher "may have been an omission" and has been corrected. On twelve payments totalling N228,338,877.13, the auditors computed that contractors were overpaid by N949,053.69 because too little tax was deducted; the centre said it deducts according to the terms of each contract letter. N527,763.58 of internally generated revenue had not been remitted to the Consolidated Revenue Fund; the centre said it would comply.
Part of the centre's capital vote is for projects outside its field. In 2023, N120,000,000 of its N248,409,434 capital vote, 48.3 per cent, went on two lines for solar street lights in the Mangu/Bokkos federal constituency of Plateau State. In 2026, N525,000,000 of N728,537,419, or 72.1 per cent, is in five lines for sewing machines and freezers in the Adavi/Okehi federal constituency of Kogi State, classrooms in the Ilorin East/South federal constituency of Kwara State, solar street lights in six named communities in Borno State and shuttle buses in Imo North senatorial district. The audit does not examine any of these lines.
The documents leave much open. They do not show what the N16.62 billion of assets consists of, how it was valued, or whether any of it has been insured since. They do not show who approved the peculiar allowance beyond "management", on what authority, or whether the payroll the auditors examined is the IPPIS payroll the centre refers to. "No evidence" records what the auditors were shown; it does not establish that money was lost, and nothing in these records establishes that anyone acted unlawfully. Whether the Public Accounts Committees have taken up the queries is not in the records. The centre was not asked for comment before publication.
What this rests on
Office of the Auditor-General for the Federation, 2024 Annual Report on Non-compliance (Vol. II), section on the National Metallurgical Development Centre, Jos, printed pages 702 to 713 (PDF pages 267 to 278), period 1 January to 31 December 2023: heading and period p.702; Issue 1 (under-deduction of taxes, N949,053.69) pp.702-703; Issue 2 (IGR not remitted, N527,763.58) pp.703-705; Issue 3 (extra-budgetary expenditures, N256,911,576.00, with table) pp.705-706; Issue 4 (unapproved allowances, N300,060,010.19, with monthly table) pp.706-707; Issue 5 (extra-budgetary expenditures, N54,769,299.65) pp.708-709; Issue 6 (payments without pre-payment audit, N50,516,499.65) pp.709-710; Issue 7 (mobilisation without advance payment guarantee, N23,778,000.00) pp.710-712; Issue 8 (non-insurance of assets, N16,619,185,636.00) pp.712-713. The scanned report was read from the copy on file (downloaded from oaugf.ng) and only these pages were rendered; a 12-page extract is saved with this story. 2023 Appropriation Act by sector, Ministry of Mines and Steel Development (Budget Office of the Federation), downloaded 20 November 2026: summary row for the centre p.1; detailed schedule pp.7-8 (personnel and travel lines p.7; other services, consulting, insurance premium, capital and totals p.8; capital project list p.8). The running header on p.8 reads "Ministry of Mines and Steel Development - HQTRS", but the lines continue the centre's schedule that begins on p.7 and close with its total of N1,036,787,527. 2026 Appropriation Act (PLAC copy): steel ministry summary p.1462; centre's schedule pp.1467-1469 (insurance premium and regular allowances p.1468, totals and project list p.1469); extract saved. Arithmetic re-done: 2023 Act 713,326,922 + 75,051,171 + 248,409,434 = N1,036,787,527 (printed total); personnel 621,728,679 + 30,532,748 + 61,065,495 = N713,326,922. Insurance 576,675 / 16,619,185,636 = 0.0035%; 16,619,185,636 / 576,675 = 28,819. 2026 premium 10,000,000 / 576,675 = 17.3 times; 2026 total 910,938,054 + 188,617,768 + 728,537,419 = N1,828,093,241. Issue 3 budget 713,326,922 + 13,633,217 + 21,406,237 + 1,492,471 = N749,858,847; actual 956,862,399 + 23,040,013 + 22,748,011 + 4,120,000 = N1,006,770,423; variance 1,006,770,423 - 749,858,847 = N256,911,576 = 243,535,477 + 9,406,796 + 1,341,774 + 2,627,529; salary share 243,535,477 / 256,911,576 = 94.8%; overhead overrun 9,406,796 + 1,341,774 + 2,627,529 = N13,376,099; travel 23,040,013 / 13,633,217 = 1.69 times; consulting 4,120,000 / 1,492,471 = 2.76 times. Issue 4 months 25,318,508.35 + 26,085,146.42 + 25,597,476.91 + 25,336,183.00 + 25,427,168.23 + 24,897,580.89 + 24,977,311.06 + 25,015,748.25 + 24,659,746.85 + 24,390,487.24 + 24,269,583.06 + 24,085,069.93 = N300,060,010.19 (printed total); average / 12 = N25,005,000.85. Issue 7: 30% of (60,000,000 + 19,260,000 = 79,260,000) = N23,778,000; 3 October 2023 to 27 June 2024 = 268 days (29 days in February 2024). Issue 1: 200,019,184.24 - 199,070,130.55 = N949,053.69. Seven money queries 949,053.69 + 527,763.58 + 256,911,576.00 + 300,060,010.19 + 54,769,299.65 + 50,516,499.65 + 23,778,000.00 = N687,512,202.76. 2023 capital lines 60,000,000 + 43,000,000 + 20,000,000 + 2,409,434 + 1,000,000 + 1,000,000 + 1,000,000 + 20,000,000 + 100,000,000 = N248,409,434; street lights 20,000,000 + 100,000,000 = N120,000,000 = 48.3%. 2026 capital lines 56,000,000 + 35,000,000 + 91,537,419 + 21,000,000 + 35,000,000 + 105,000,000 + 70,000,000 + 175,000,000 + 140,000,000 = N728,537,419; place-named lines 35,000,000 + 105,000,000 + 70,000,000 + 175,000,000 + 140,000,000 = N525,000,000 = 72.1%. 2026 personnel 703,229,146 + 94,866,406 + 34,607,771 + 69,215,542 + 9,019,189 = N910,938,054.
What this does not establish
What the N16,619,185,636.00 of assets consists of, how and when it was valued, and whether any asset has been insured since the audit; whether any of the 2023 premium vote of N576,675 was spent. Whether the N956,862,399 of actual salary spending includes health insurance and pension contributions, and so whether the auditors' comparison with the whole personnel vote of N713,326,922 is like for like; whether that figure includes the peculiar allowance. Who in management approved the allowance, on what authority, and how the auditors' statement that it was built into the centre's payroll squares with the centre's reply that salaries are paid by the IPPIS office of the Accountant-General; the report does not reconcile them. Which budget lines paid the N60,000,000 equipment contract and the N19,260,000 furnace contract, and whether the furnaces were reactivated. How much of the 2023 and 2026 capital votes was released and spent; no release or implementation figures were obtained. Whether the Public Accounts Committees have heard the centre. Who proposed the place-named capital lines; the Acts do not say. Nothing here alleges a crime; an audit query is not a finding of wrongdoing. The centre was not asked for comment.
What we did ourselves
Read the eight queries on the centre from the scanned audit report, rendering only those pages. Downloaded the 2023 Appropriation Act file for the Ministry of Mines and Steel Development and matched every budget figure the auditors cite (the centre's total, its personnel vote, three overhead subheads and the insurance premium line) to the Act. Separated the salary part of the overspending query from the overhead part, and showed that the auditors' salary budget is the Act's whole personnel vote rather than its salaries line. Re-added the twelve monthly allowance payments, the overspending table, the mobilisation fees and the seven money queries, counted the days between the mobilisation payment and the start of the bond cover, and re-added the centre's 2023 and 2026 capital project lists. Read the centre's 2026 lines for insurance, allowances and capital.
Sources for this report
(A) Office of the Auditor-General for the Federation, 2024 Annual Report on Non-compliance (Vol. II), National Metallurgical Development Centre, Jos, pp.702-713; 2023 Appropriation Act by sector, Ministry of Mines and Steel Development, National Metallurgical Development Centre, Jos, pp.1, 7 and 8; 2026 Appropriation Act, National Metallurgical Development Centre, Jos, pp.1462 and 1467-1469.
- 2024 Annual Report on Non-compliance (Internal Control Weakness), Vol. II · Office of the Auditor-General for the Federation · 2026
- 2023 Appropriation Act by sector: Federal Ministry of Mines and Steel Development · Budget Office of the Federation · January 2023
- 2026 Appropriation Act (copy published by PLAC) · National Assembly of the Federal Republic of Nigeria · April 2026
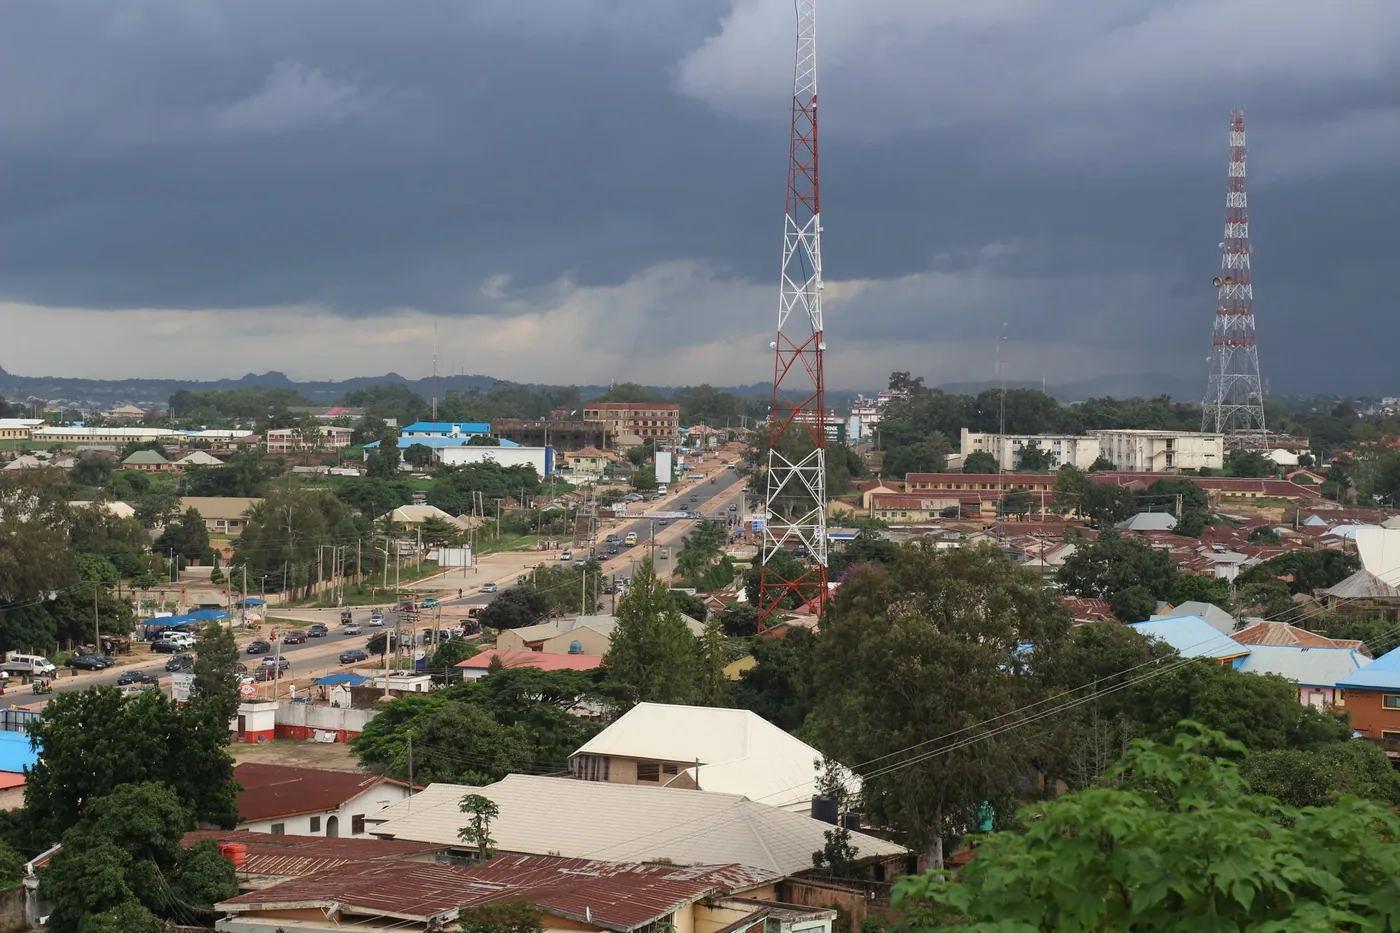
- File:Jos, looking south from Anglo-Jos.jpg (cover photograph) · Wikimedia Commons · 20 August 2016
Confidence: high. This is our own assessment of whether the event occurred as described, separate from the grade, which describes what kind of thing the claim rests on.
Not obtained: where the underlying document is named above but not linked, we did not hold a copy at the time of publication. We purchase nothing and request nothing in our own name.
Corrections
None on this report. If you find an error, it will be published here, at the same length, with the date it was found, and the original wording will remain visible above it.
Dr VeroInvestigations editor, Vero Record
Reads the Nigerian public record that others leave unread: budgets, audit reports, court files and registers. Every claim on this page carries the grade of the document behind it, and the report says what that document does not establish.
All 196 reportsHow we grade evidenceAdd Vero Record as a preferred source on Google