NAIC gave no response to any of 36 audit queries, led by N1.09bn of contracts; the 2026 Act gives the insurer N5bn for two centres in Kano and Kaduna
The Auditor-General's 2024 report raises 36 queries against the Nigerian Agricultural Insurance Corporation and records "No response" to every one, among them N1,085,966,438.40 of contracts approved without the political head's confirmation and a N200,000,000 training item the auditors say was split into six lots worth N291,265,875. The 2024 Appropriation Act gave the corporation N1,333,960,932. The 2026 Act gives it N6,659,420,406, of which N5bn is for two centres in Kano and Kaduna, a "modern skill acquisition center" and a "modern acquisition center", whose names the same Act elsewhere places in Ebonyi and Abia.
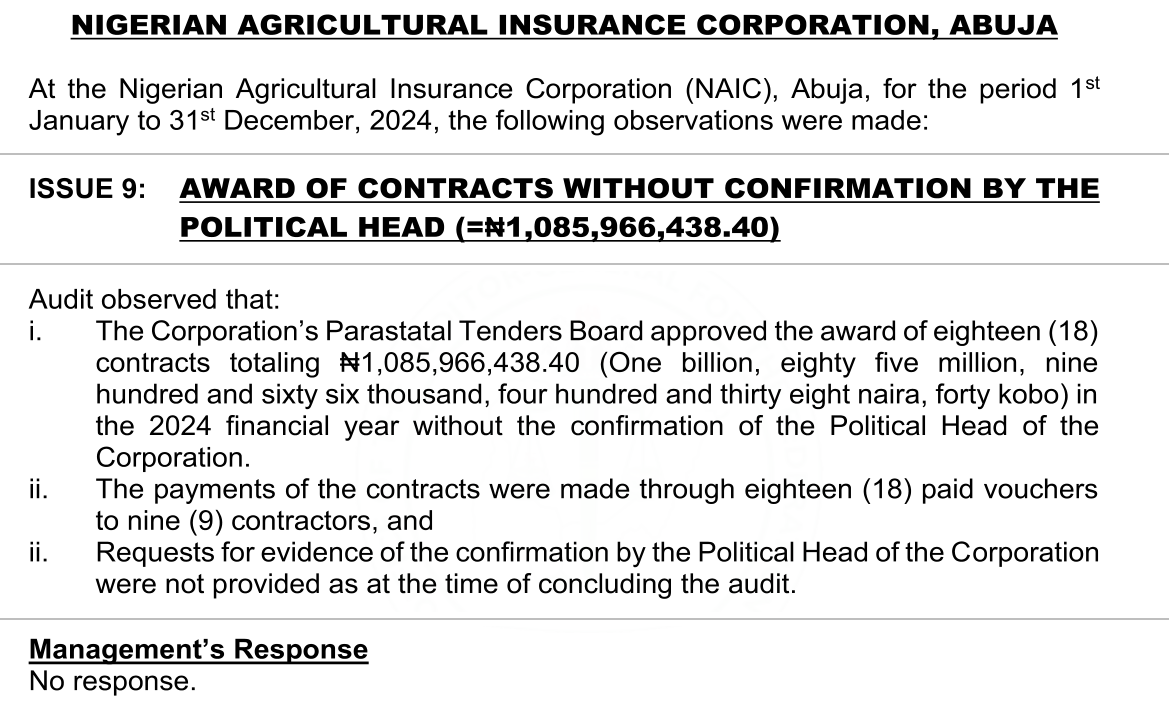
The Auditor-General's report on federal bodies for 2024 raises 36 queries against the Nigerian Agricultural Insurance Corporation (NAIC), the Abuja corporation that insures farmers and, by law, receives the federal and state shares of their premium subsidy. Under all 36, the space for the management's answer reads "No response." The largest contract query covers 18 contracts worth N1,085,966,438.40 that the corporation's own tenders board approved in 2024 without its political head's confirmation, without bills of quantities and without a market survey. The 2026 Appropriation Act gives NAIC N6,659,420,406, almost exactly five times the N1,333,960,932 of the 2024 Act, and N5,000,000,000 of it is for two centres in Kano and Kaduna States, a "modern skill acquisition center" and a "modern acquisition center". An audit query records what the auditors asked for and did not receive. It is not a finding of wrongdoing, and no court has made one.
The report is the Auditor-General for the Federation's Annual Report on Non-compliance and Internal Control Weaknesses in Ministries, Departments and Agencies for the year ended 31 December 2024, sent to the Clerk to the National Assembly on 17 July 2026. NAIC's section runs from page 37 to page 75 of Volume I and covers 1 January to 31 December 2024. Each issue sets out the rule, what the auditors observed, the management's response, the auditor's evaluation and recommendations to the Public Accounts Committees of the National Assembly. For NAIC, every evaluation says the findings "remain valid" because the management did not respond. The report quotes the corporation's own law, the NAIC Act of 1993: farmers' premiums may be subsidised by up to 50 per cent, paid by the Federal Government and the states "in the proportion of 37.5% and 12.5% respectively", within the first quarter of the following year. In the Appropriation Acts, NAIC has no personnel or overhead allocation. All of its federal money is capital, and until this year most of it was the federal premium subsidy.
Four of the 36 queries concern the same money. Issues 9, 10, 14 and 15 each carry the figure N1,085,966,438.40, for 18 contracts paid through 18 vouchers to nine contractors. The auditors say the awards were not confirmed by the political head, as section 66(5) of the Finance Act 2020 requires; that no evidence of due diligence on the contractors was produced; that the contract sums were not broken down into bills of quantities or a bill of engineering measurement and evaluation; and that no market survey report was produced to justify the prices, the tenders board minutes showing no in-house estimate. The four headings add to N4,343,865,753.60, but they describe one set of contracts, and this report counts the sum once. Issue 13 says the Bureau of Public Procurement allowed restricted tendering for ten capital projects in 2024 on condition that no bidder be shortlisted for more than one lot, and that NAIC shortlisted some bidders for more than one lot "and even awarded multiple contracts to the same bidders", worth N483,598,898.40. Issue 17 covers two construction contracts on which N266,557,265 was paid without valuation certificates; the auditors did not see the working alternative power supply said to have been installed at the headquarters, nor pictures of work on the other project. The audit does not say whether these contracts form part of the N1,085,966,438.40.
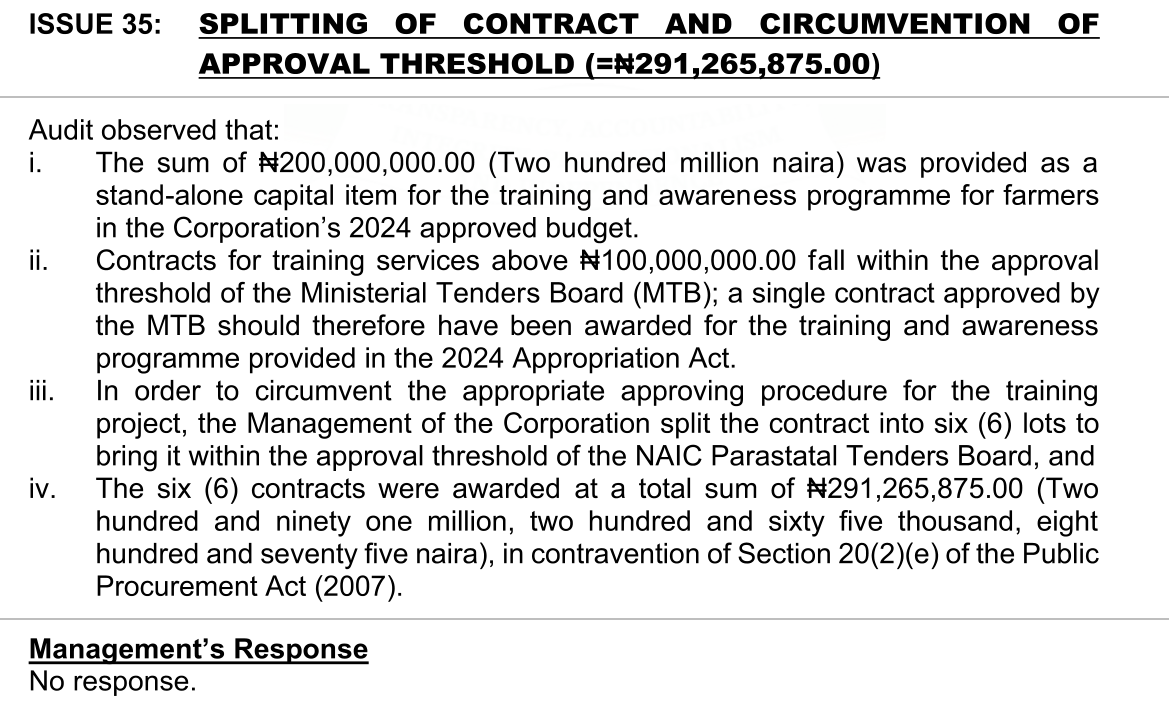
The most specific procurement query is Issue 35. The auditors write that N200,000,000 "was provided as a stand-alone capital item for the training and awareness programme for farmers in the Corporation's 2024 approved budget". Training contracts above N100,000,000 fall to the Ministerial Tenders Board, so, in their words, a single contract approved by that board should have been awarded "for the training and awareness programme provided in the 2024 Appropriation Act". Instead, they say, the management split it into six lots to bring it within the threshold of NAIC's own parastatal tenders board, and the six contracts were awarded for a total of N291,265,875. That is N91,265,875 more than the N200,000,000 the audit says was provided, a difference the report does not discuss. The audit cites the Public Procurement Act's rule against splitting tenders. Citing a section of the Act is not a finding that an offence was committed.
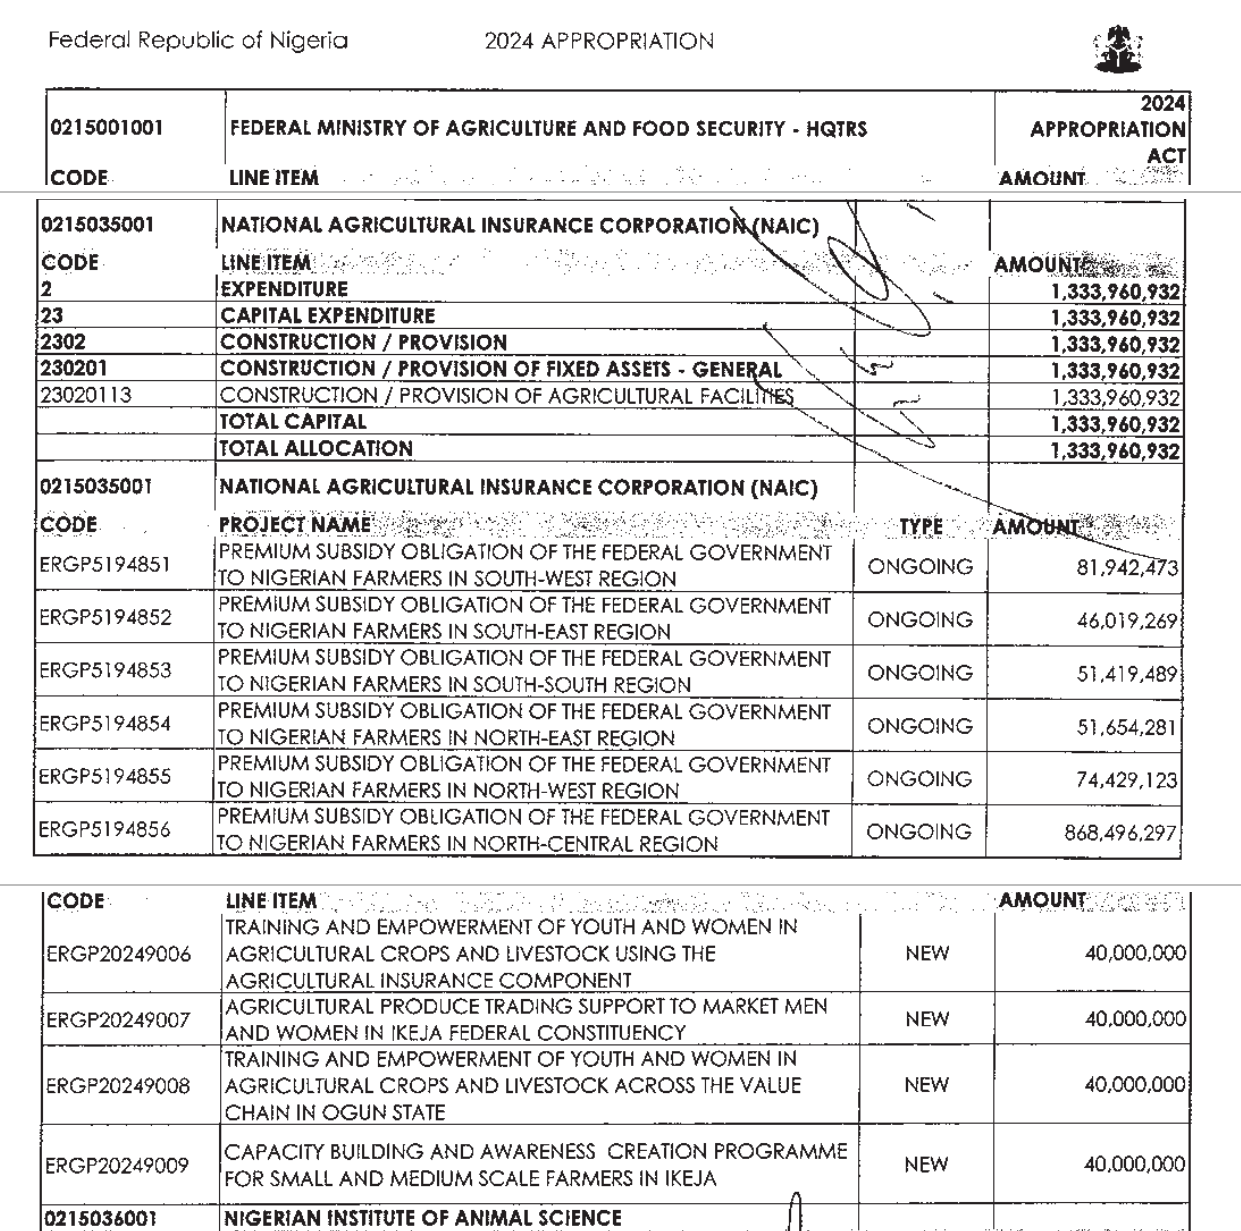
The 2024 Appropriation Act does not show a N200,000,000 training item under NAIC. It gives the corporation N1,333,960,932, all capital (page 563). Six lines, N1,173,960,932 in all, are the "premium subsidy obligation of the Federal Government to Nigerian farmers", one for each geopolitical zone; the North-Central line alone is N868,496,297. The other four lines, on page 564, are N40,000,000 each and marked new: training and empowerment of youth and women "using the agricultural insurance component", produce trading support for market men and women in the Ikeja federal constituency, training across the value chain in Ogun State, and capacity building for small and medium scale farmers in Ikeja. Three of the four are training or awareness lines, N120,000,000 together. Separately, the audit's Issue 16 records that NAIC awarded and executed four constituency projects in 2024 worth N154,464,000, certified them fully completed and paid in full, without the certification of the Federal Ministry of Special Duties and Inter-Governmental Affairs that a 2015 circular requires. The Act's four N40,000,000 lines add to N160,000,000, N5,536,000 more than the audit's figure. The audit does not name its four projects, so the record does not establish that they are these four lines, or where the N200,000,000 training item was appropriated.
Many of the 36 queries concern pay and allowances, and in each the auditors say NAIC could not produce approval from the National Salaries, Incomes and Wages Commission. Fifteen staff received N40,976,379.72 in 2024 as the salaries of domestic staff, paid monthly at Grade Level 03 and separately from their own salaries, in bands the audit lists as six domestic staff for the Managing Director, five for Executive Directors, three for General Managers, three for Deputy General Managers and one for Assistant General Managers. Thirteen staff received N2,400,000 as Sallah bonus for personal domestic staff who, the audit says, are not employees of the corporation. Children allowance of N54,662,061.74, medical allowance of N20,336,188.46 for top management, and N17,621,800 paid to the Managing Director and Executive Directors to buy diesel "for their personal use" are queried on the same ground. Issue 1 says 56 promoted staff were placed above the correct salary step, an overpayment of N6,192,103.32.
Two Toyota Land Cruisers bought for the Executive Directors, for N51,918,100 on 10 March 2022 and N46,762,500 on 25 October 2021, were disposed of before the end of their four-year depreciation period and sold to the same directors as part of their severance package, without a competitive process or an independent valuation, the audit says; its table gives scrap values of N4,153,447.93 and N3,390,281.25. Six vehicles carried at N117,038,888 in the 2023 vehicle register were missing from the 2024 register and were not seen at inspection. And by a voucher dated 10 December 2024, NAIC paid US$58,169.90 to the Nigerian National Petroleum Company as an insurance claim for a fire on 12 December 2018, under a policy that ran from 1 April 2018 to 1 April 2019. According to the audit, the claim was submitted in 2024, the policy file held no evidence of a 2018 premium, and the money went to an NNPC account with Standard Chartered Bank in London rather than to its Treasury Single Account at the Central Bank of Nigeria.
The largest single sum in NAIC's section is money owed to it. The 36 states and the Federal Capital Territory Administration owed the corporation N1,989,535,779.20 at 31 December 2024, the auditors say: their 12.5 per cent share of the premium subsidy. Section 9(4) of the NAIC Act, as the audit quotes it, provides that where a state defaults, "the Federal Government shall cause the amount to be deducted from funds due to the defaulting State and remitted to the Corporation". The auditors write that NAIC "failed to activate" that section. The same part of the report records N265,282,048.85 of tenancy rent owed to the corporation and uncollected at the end of 2024.
Against these queries, the 2026 Appropriation Act changes what NAIC is funded to do. Its N6,659,420,406 on page 849 is again all capital. The six premium subsidy lines come to N1,659,420,406, down from N2,370,600,580 in the 2025 Act; each is 70 per cent of its 2025 figure, to the naira after rounding. The other N5,000,000,000 is two lines: N2,502,000,000 for the "construction/equipment of Umuobuna modern skill acquisition center, Garko/Wudil LGA, Kano State" and N2,498,000,000 for the "construction /equipment of Item modern acquisition center, Makarfi LGA Kaduna State", both in multiple lots and both marked "ongoing". Neither line appears in NAIC's pages of the 2024 or 2025 Acts. Together they are 75.1 per cent of the corporation's 2026 allocation, and each on its own is larger than its whole 2024 allocation.
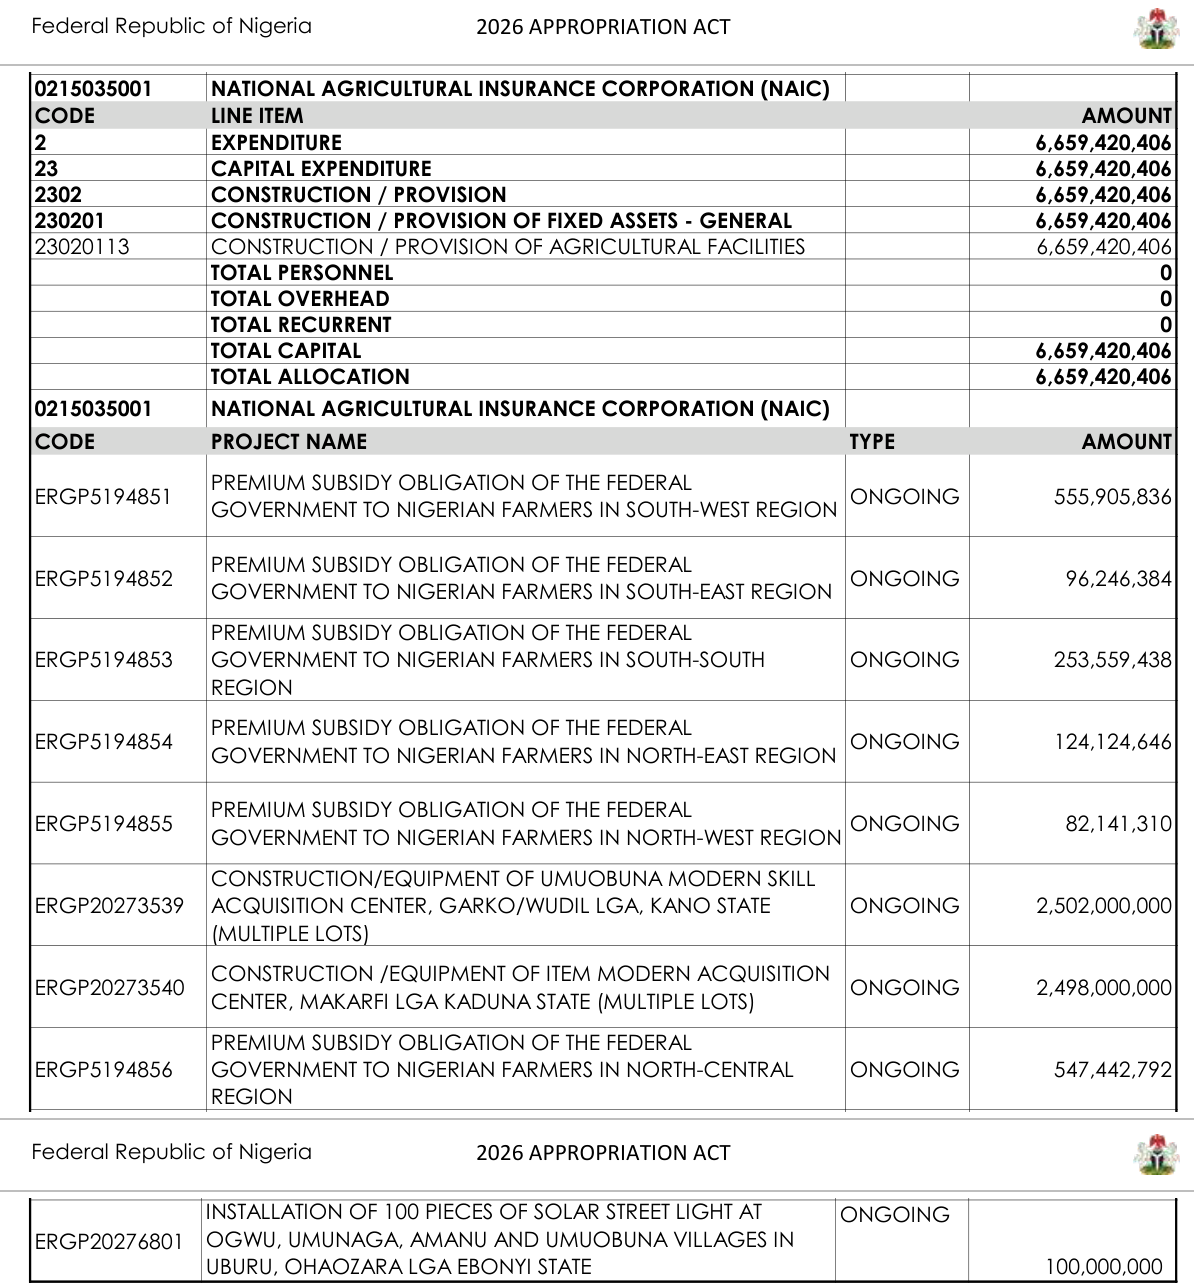
The two names appear elsewhere in the same Act attached to other states. A street light line on page 1461 places Umuobuna among four villages in Uburu, Ohaozara LGA, Ebonyi State; on page 678 and later pages, Item is a community in Bende LGA, Abia State. These records appear inconsistent. Vero Record did not establish whether places of the same names exist in Garko, Wudil or Makarfi, or whether the names are drafting errors; the Act gives no other description of either centre. The 2025 Act has a mismatch of its own on NAIC's page 669: the listed projects, six premium lines and N100,000,000 for 500KVA transformers in Ogun East Senatorial District, add to N2,470,600,580, while the stated allocation is N2,370,600,580.
Parts of the record favour the corporation. "No response" means no answer reached the auditors before the report closed; in September Vero Record reported that the National Cash Transfer Office had answered the Auditor-General although the report records "No response" to all eight of its queries. The N1,989,535,779.20 is money owed to NAIC, not money it spent, and the deduction power in its Act belongs to the Federal Government. The 30 per cent cut to the premium lines matches the instruction, reported by Vanguard on 9 December 2025, in the Ministry of Budget and Economic Planning's 2026 budget call circular that agencies carry 70 per cent of their 2025 budget into 2026. The two centre lines were enacted by the National Assembly and signed by the President, and nothing in the Act shows that NAIC asked for them. The audit lists risks such as loss of public funds for most issues. It does not state that any loss occurred.
The documents do not establish what the 18 contracts were for, who received them, or whether the work was done; the audit names no contractor. They do not establish where the N200,000,000 training item was appropriated, whether the four constituency projects are the four N40,000,000 lines in the 2024 Act, whether NAIC answered the auditors after the report closed, or whether the Public Accounts Committees have taken up any of the 36 issues. Vero Record did not contact the corporation before publication. Its answers, and the committees' findings when they come, are the next records to read.
What this rests on
Office of the Auditor-General for the Federation, Annual Report on Non-compliance/Internal Control Weaknesses in MDAs for the year ended 31 December 2024, Volume I (scanned; transmittal letter dated 17 July 2026, p.ii): Nigerian Agricultural Insurance Corporation, Abuja, Issues 1 to 36, printed pp.37 to 75 (PDF pp.73 to 111), period 1 January to 31 December 2024. Pages were rendered and read with OCR, and every figure quoted was checked against the page image. Count: 36 issues and 36 management responses, every one "No response". 2024 Appropriation Act (scanned), NAIC code 0215035001, printed pp.563 and 564 (PDF pp.593 and 594) and summary PDF p.438; 2025 Appropriation Act as passed, pp.429 and 669; 2026 Appropriation Act, pp.484, 678, 849 and 1461. Arithmetic re-done: 2024 Act premium lines 81,942,473 + 46,019,269 + 51,419,489 + 51,654,281 + 74,429,123 + 868,496,297 = 1,173,960,932; plus 4 x 40,000,000 = 160,000,000 gives 1,333,960,932, the printed total; three training or awareness lines 3 x 40,000,000 = 120,000,000; 160,000,000 - 154,464,000 = 5,536,000. 2025 Act premium lines 794,151,194 + 137,494,834 + 362,227,769 + 177,320,923 + 117,344,729 + 782,061,131 = 2,370,600,580, equal to the printed total; with the 100,000,000 transformer line the listed projects add to 2,470,600,580. 2026 Act premium lines 555,905,836 + 96,246,384 + 253,559,438 + 124,124,646 + 82,141,310 + 547,442,792 = 1,659,420,406; plus 2,502,000,000 + 2,498,000,000 = 5,000,000,000 gives 6,659,420,406, the printed total; each 2026 premium line equals 0.7 x its 2025 line rounded to the naira (794,151,194 x 0.7 = 555,905,835.8; 137,494,834 x 0.7 = 96,246,383.8; 362,227,769 x 0.7 = 253,559,438.3; 177,320,923 x 0.7 = 124,124,646.1; 117,344,729 x 0.7 = 82,141,310.3; 782,061,131 x 0.7 = 547,442,791.7); 2,370,600,580 - 1,659,420,406 = 711,180,174 (30.0 per cent); 5,000,000,000 / 6,659,420,406 = 75.1 per cent; 6,659,420,406 / 1,333,960,932 = 4.99; 2,502,000,000 and 2,498,000,000 each exceed 1,333,960,932. Audit: 4 x 1,085,966,438.40 = 4,343,865,753.60 (not added, one set of contracts); 291,265,875 - 200,000,000 = 91,265,875; Land Cruisers 51,918,100 + 46,762,500 = 98,680,600, the printed total; scrap values 4,153,447.93 + 3,390,281.25 = 7,543,729.18. Internal points in the audit text: Issue 35 places the N200,000,000 item both in "the Corporation's 2024 approved budget" and in "the 2024 Appropriation Act", and the Act's NAIC pages carry no such line; the same N1,085,966,438.40 heads Issues 9, 10, 14 and 15; Issue 30 recommends that money owed to the corporation by the states be recovered and remitted "to the Treasury". For every issue cited, the heading figure matches the recommendation figure. Context only: Vanguard, 9 December 2025, on the 2026 budget call circular's 70 per cent carry-over; Daily Trust, 3 September 2026, on the report's NAIC vehicle finding.
What this does not establish
What the 18 contracts worth N1,085,966,438.40 were for, who the nine contractors are, whether the work or services were delivered, and whether the contracts were paid from appropriated funds or from the corporation's own income; the audit names no contractor and no project. Where the N200,000,000 training item of Issue 35 was appropriated: it is not among NAIC's lines in the 2024 Appropriation Act as passed, and Vero Record did not examine any supplementary, amended or re-enacted 2024 budget or the corporation's internal budget. Whether the four constituency projects of Issue 16 are the four N40,000,000 lines in the 2024 Act. Whether NAIC sent answers to the auditors after the report closed, and what the Public Accounts Committees have done with the 36 issues. Who proposed the two 2026 centre lines, why they are listed under an insurance corporation, whether places called Umuobuna or Item exist in Garko, Wudil or Makarfi, and how much of the 2026 allocation has been released. Why the 2025 Act lists N100,000,000 more in NAIC projects than its stated total. Whether any of the queried payments involved a loss of public money or any offence; an audit query is not a finding of wrongdoing, and no court has found any. The corporation was not asked for comment before publication.
What we did ourselves
Read all 39 pages of NAIC's section in Volume I of the 2024 audit report from page images and counted the issues and the management responses: 36 and 36, every one "No response". Separated the four issues that repeat one N1,085,966,438.40 figure so that it is counted once. Found NAIC's entries in the 2024, 2025 and 2026 Appropriation Acts and re-added every line against the printed totals, which showed that each 2026 premium subsidy line is 70 per cent of its 2025 figure, that N5bn of the 2026 allocation is for two centres absent from the earlier Acts, and that the 2025 project list exceeds its total by N100m. Set Issue 35's N200,000,000 training item and Issue 16's four constituency projects against the 2024 Act's NAIC lines. Searched the 2026 Act for the two centre names and found Umuobuna placed in Ebonyi State and Item in Abia State elsewhere in the same Act.
Sources for this report
(A) Office of the Auditor-General for the Federation, Annual Report on Non-compliance/Internal Control Weaknesses in MDAs for the year ended 31 December 2024, Volume I, Nigerian Agricultural Insurance Corporation, Abuja, Issues 1 to 36, pp.37 to 75; 2024 Appropriation Act, NAIC (0215035001), pp.563 to 564; 2025 Appropriation Act, p.669; 2026 Appropriation Act, pp.849, 1461 and 678.
- Auditor-General for the Federation's Annual Report on Non-compliance/Internal Control Weaknesses in MDAs for the year ended 31 December 2024, Vol. I · Office of the Auditor-General for the Federation · 17 July 2026 (transmittal letter)
- 2024 Appropriation Act · National Assembly / Budget Office of the Federation · 2024
- 2025 Appropriation Act as Passed · National Assembly / Budget Office of the Federation · 2025
- 2026 Appropriation Act (copy published by PLAC) · National Assembly of the Federal Republic of Nigeria · April 2026
- FG mandates MDAs to upload 70% of 2025 budget into 2026 fiscal year · Vanguard · 9 December 2025
- 25 MDAs, varsities, others flagged in N1.34trn audit lapses · Daily Trust · 3 September 2026
- File:Farm workers threshing maize at Makarfi Local Government of Kaduna State Nigeria 02.jpg · Wikimedia Commons (MKALM7, CC BY-SA 4.0) · 21 October 2017
Confidence: high. This is our own assessment of whether the event occurred as described, separate from the grade, which describes what kind of thing the claim rests on.
Not obtained: where the underlying document is named above but not linked, we did not hold a copy at the time of publication. We purchase nothing and request nothing in our own name.
Corrections
None on this report. If you find an error, it will be published here, at the same length, with the date it was found, and the original wording will remain visible above it.
Dr VeroInvestigations editor, Vero Record
Reads the Nigerian public record that others leave unread: budgets, audit reports, court files and registers. Every claim on this page carries the grade of the document behind it, and the report says what that document does not establish.
All 181 reportsHow we grade evidenceAdd Vero Record as a preferred source on Google