Niger's audited 2025 accounts add N92.92bn of VAT to FAAC totals that federal tables show already include it; its budget report counts it once
Niger State's audited accounts for 2025 put its revenue from the Federation Account at N362.57bn; its own fourth-quarter budget report says N288.14bn. The federal Accountant-General's tables for all twelve 2025 FAAC meetings show that the monthly figures the accounts call statutory allocation, N195.38bn in all, are the federal total gross amounts, VAT included. Note 1 then adds the N92.92bn of VAT again. Without the second count, audited FAAC revenue is N269.65bn. The state's debt figures, by contrast, agree with the Debt Management Office to the kobo.
Niger State's audited financial statements for 2025, signed by the Accountant-General, Saidu Abdullahi, and certified by the State Auditor-General, Ahmed Abubakar, as giving "a true and fair view", put the state's revenue from the Federation Account at N362,566,406,977.20. The state's own budget performance report for the fourth quarter of 2025, published in January, puts the same revenue at N288,141,123,505.56. Neither document explains the N74.43bn difference. Set against the federal Accountant-General's allocation tables for all twelve 2025 meetings of the Federation Account Allocation Committee (FAAC), the accounts show where most of it comes from: they add the state's N92,917,444,389.86 share of value added tax to monthly totals that already contain it.
A supplementary note on page 93 of the accounts lists, month by month, what it calls the government share of FAAC: a net receipt, an amount deducted at source and a total. The twelve totals add to N195,380,083,339.30, and Note 1 carries that figure as the state's share of statutory allocation. Table III of the federal disbursement reports, which sets out each state's allocation at every FAAC meeting, puts Niger's gross statutory allocation for the same twelve meetings at N89,391,435,885.28. The accounts' figure is N105,988,647,454.02 larger, 2.19 times the federal one.
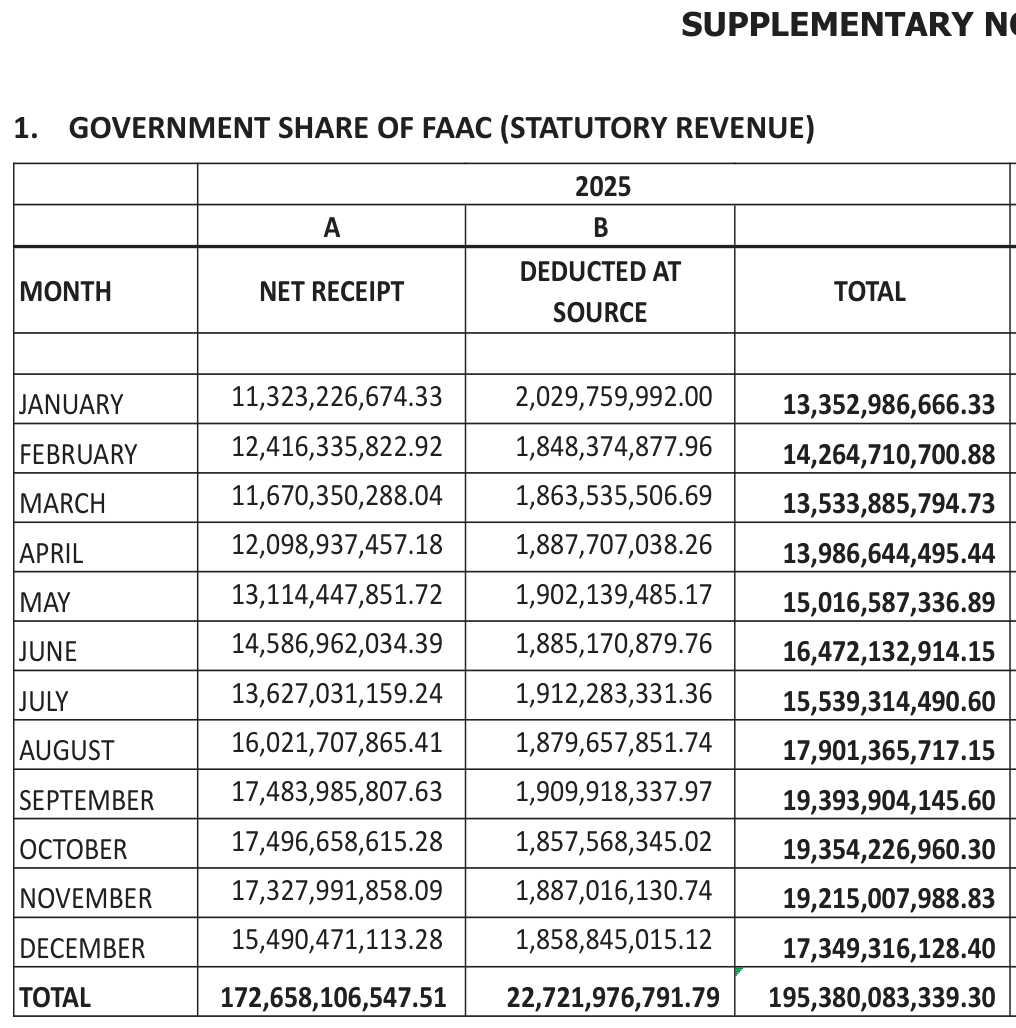
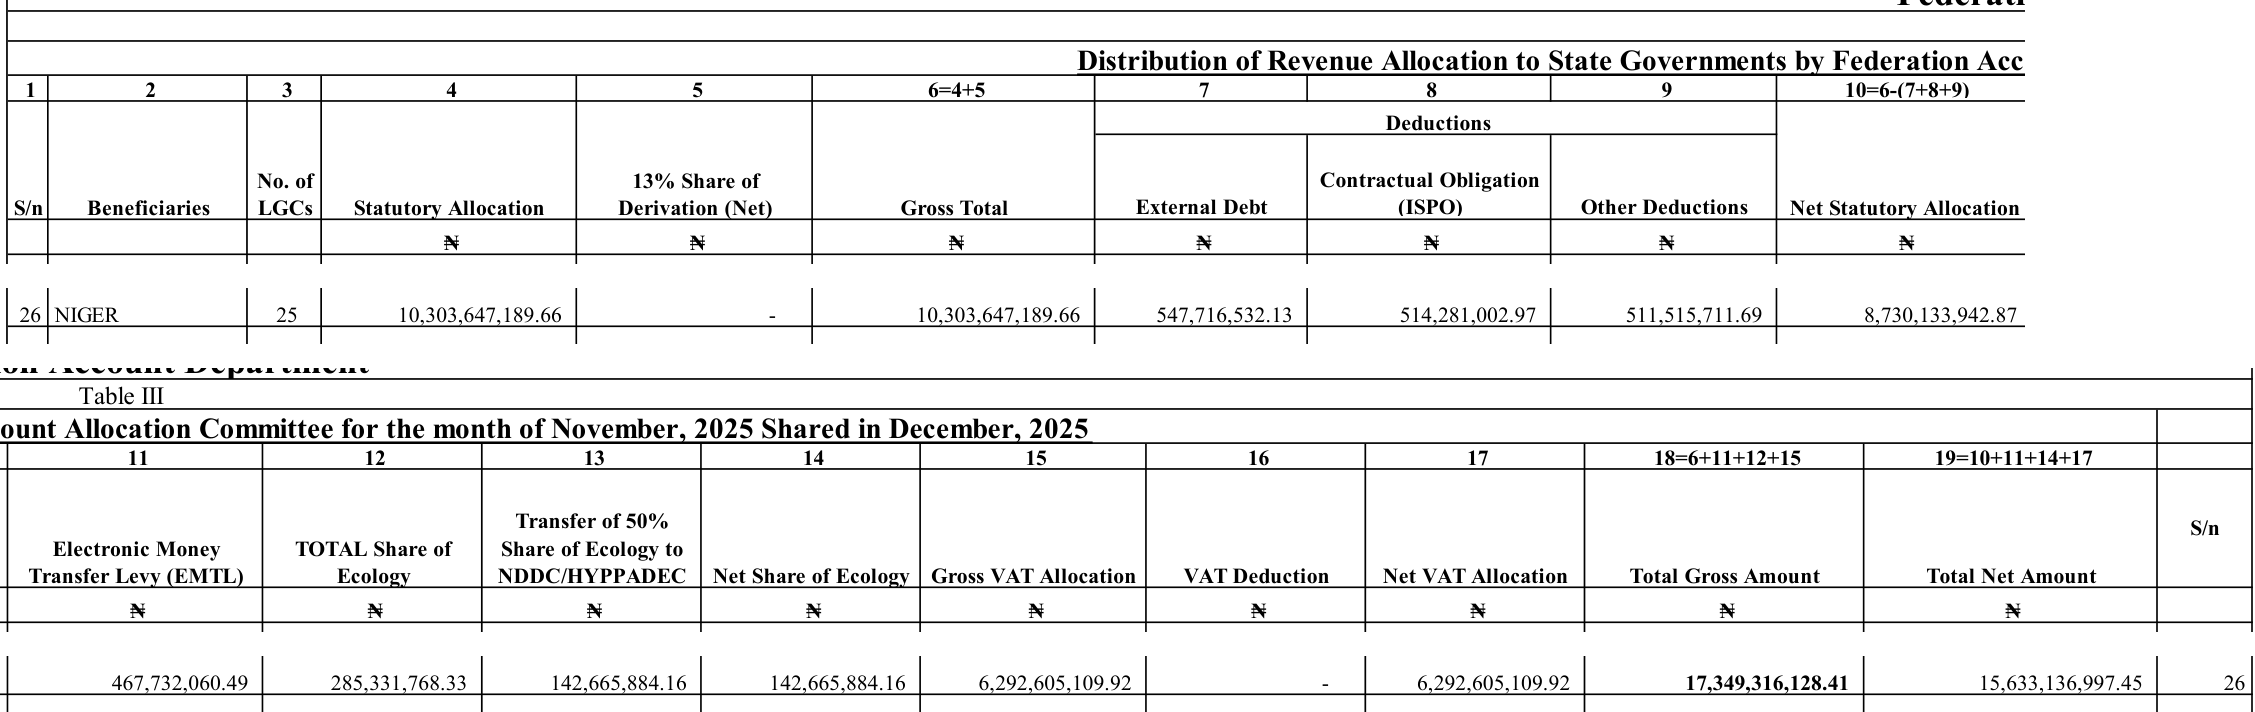
The monthly rows show why. For December 2025, when FAAC shared November's revenue, the audited total is N17,349,316,128.40. The federal row for Niger that month gives a statutory allocation of N10,303,647,189.66, a share of the Electronic Money Transfer Levy (EMTL) of N467,732,060.49, an ecology share of N285,331,768.33 and gross VAT of N6,292,605,109.92. The table's "Total Gross Amount", defined as the sum of those four columns, is N17,349,316,128.41. The audited figure is that total, VAT included. In nine of the twelve months (January, April, May, June and August to December) the audited total equals the federal total gross amount, in eight of them to within one kobo and in May to within N108.64. In February, March and July the audited figure is lower than the federal total, by N1.55bn, N1.49bn and N0.83bn, but in each of those months it is larger than everything on the federal row other than VAT (N14.26bn against N7.25bn in February, N13.53bn against N8.02bn in March and N15.54bn against N9.01bn in July), so VAT is inside those months too.
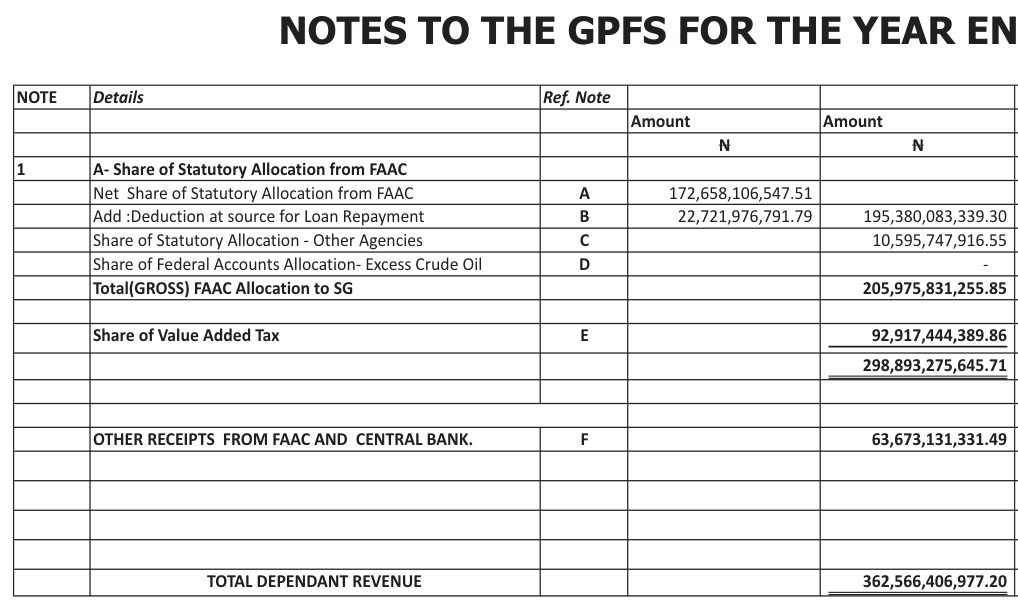
Note 1 on page 36 then builds the revenue figure on top of the monthly totals. It adds the N172,658,106,547.51 received net and the N22,721,976,791.79 deducted at source to reach N195,380,083,339.30, adds N10,595,747,916.55 from "other agencies" for a "Total (GROSS) FAAC Allocation to SG" of N205,975,831,255.85, and then adds a "Share of Value Added Tax" of N92,917,444,389.86 to reach N298,893,275,645.71. With N63,673,131,331.49 of other receipts from FAAC and the Central Bank, the total is N362,566,406,977.20. The VAT schedule on page 94 shows where the N92.92bn comes from: twelve monthly figures, each identical to the kobo to the gross VAT column of the federal tables, among them the N6,292,605,109.92 for December that is already part of December's N17,349,316,128.40.
Two smaller items follow the same pattern. The N10.60bn from other agencies includes the EMTL, N4,972,509,433.08 for the year; in the nine months where the audited totals equal the federal total gross amount, that month's EMTL, N3,952,663,900.68 in all, is already inside the total. And four of the 19 entries in the list of other receipts on page 95 carry amounts identical to columns already within those months' totals: N2,899,766,655.49, the January exchange gain; N4,811,784,669.73, the April net statutory allocation; and N592,923,354.31 and N563,928,204.12, the May and June exchange gains (the last differs from the federal figure by one kobo). Together they come to N8,868,402,883.65. The accounts do not say whether these are the same payments recorded twice, and they are left out of the figures that follow.
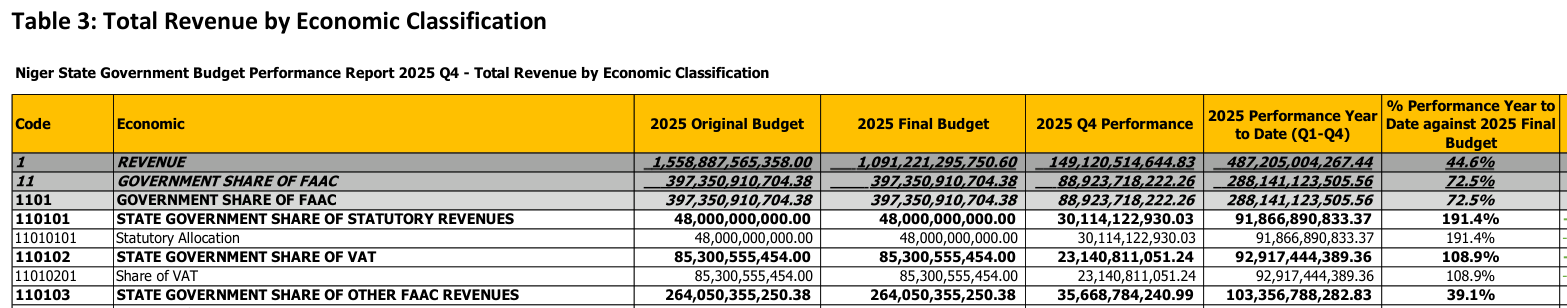
The state's own budget report counts VAT once. Table 3 on page 10 of the fourth-quarter 2025 report gives statutory allocation of N91,866,890,833.37, VAT of N92,917,444,389.36 and other FAAC revenues of N103,356,788,282.83, which add to the N288,141,123,505.56 it reports. Its statutory figure is N2,475,454,948.09 above the federal gross of N89.39bn, and its VAT figure is 50 kobo below the audited one. Take the second count of VAT out of the audited total and it falls to N269,648,962,587.34, which is N18,492,160,918.22 below the budget report rather than N74.43bn above it. The rest of the gap lies in other FAAC receipts, N103.36bn in the report against N10.60bn plus N63.67bn in the accounts, which neither document reconciles line by line.
The larger figure runs through the audited statements. The Statement of Budget Comparison on page 34 sets FAAC revenue of N362,566,406,977 against a final budget of N432,350,910,704, a performance of 83.9 per cent; the budget report measures its N288.14bn against a final FAAC budget of N397,350,910,704.38, or 72.5 per cent. The two documents' FAAC budgets differ by N35bn, and neither explains that either. The cash-flow statement on page 30 lists N205,975,831,256 of statutory allocation and N92,917,444,390 of VAT as separate inflows, within total operating inflows of N561,044,916,367. The State Auditor-General's report in Part II of the same volume repeats statutory allocation of N362.57bn and receipts of N561.04bn for 2025, and a surplus for the year of N277,315,623,522, without comment on the VAT line.
The cash-flow statement nonetheless reconciles to the closing cash balance. Its net flow for the year, N21,492,326,985, added to the opening N54,603,342,532, gives N76,095,669,517, the cash balance on the balance sheet. If one inflow is overstated by N92.92bn and the closing balance is correct, an equal amount must be overstated among the outflows, or understated among other inflows, for the statement to balance. The documents do not show where. One line differs from the budget report by a similar sum: audited capital expenditure is N451,119,440,555, against N350,917,003,510.60 in the fourth-quarter report, a difference of N100,202,437,044.40. Nothing in either document links the two, and the capital figures may differ for other reasons, including the report's own note that some ministries and agencies had not submitted data.
On debt, the accounts and the federal record agree. Note 24 on page 90 gives domestic loans of N99,843,580,316.93 at 31 December 2025; with contractors' arrears of N1,081,734,816.57 and pension arrears of N41,747,161,012.40, the note's total is N142,672,476,145.90, the same to the kobo as the Debt Management Office's domestic debt figure for Niger on that date. The accounts' external loans, N201,775,673,446.76, correspond to the DMO's $140,585,037.65 at N1,435.26 to the dollar, although the DMO lists $25,068,193.26 of it as bilateral and the accounts list no bilateral loans. The VAT figure itself is correct in every month; the problem is only that it is counted a second time.
The audited cash balance also matters for 2026. The 2026 budget assumed an opening balance of N27,508,089,852.13, within one kobo of the fourth-quarter report's receipts of N541,808,346,798.97 less its spending of N514,300,256,946.85. The audited accounts put cash at 31 December 2025 at N76,095,669,517. The state's 2026 second and third-quarter reports, the latter published on 30 October, record an actual opening balance of N75,876,574,214.16, 275.8 per cent of the budgeted figure and N219,095,302.84 below the audited one. On this point the state's later reports follow the audited figure rather than the budget's assumption.
The documents establish a counting error in how the accounts present FAAC revenue. They do not establish that any money is missing: the VAT amounts match the federal tables, the closing cash ties to the balance sheet and the debt ties to the DMO. Vero Record did not put the figures to the Niger State Accountant-General or the State Auditor-General before publication; the comparison above rests entirely on their own documents and the federal tables.
What this rests on
Niger State Government, Audited Financial Statements for the year ended 31 December 2025 (164 pages, uploaded to the Niger Open Government Portal on 30 July 2026): audit certificate p.25, balance sheet pp.28 to 29, cash-flow statement pp.30 to 31, Statement of Budget Comparison p.34, Note 1 p.36, Note 24 p.90, supplementary notes pp.93 to 95, State Auditor-General's tables pp.134 and 136. Niger State Budget Performance Report, fourth quarter 2025 (Table 1 p.7, Table 3 p.10), and second and third quarters 2026 (Table 1 p.7). Office of the Accountant-General of the Federation, Table III of the twelve FAAC disbursement reports for January to December 2025, Niger row. DMO states' domestic and external debt tables at 31 December 2025. Arithmetic re-done: Note 1 172,658,106,547.51 + 22,721,976,791.79 = 195,380,083,339.30; + 10,595,747,916.55 = 205,975,831,255.85; + 92,917,444,389.86 = 298,893,275,645.71; + 63,673,131,331.49 = 362,566,406,977.20. Federal gross statutory, Niger, January to December 2025: 2,585,253,652.02 + 5,297,423,392.89 + 5,646,629,618.92 + 6,513,398,903.76 + 6,649,416,486.44 + 6,066,818,116.53 + 7,314,617,273.41 + 9,462,957,112.46 + 10,552,256,607.00 + 8,967,566,576.14 + 10,031,450,956.05 + 10,303,647,189.66 = 89,391,435,885.28; 195,380,083,339.30 - 89,391,435,885.28 = 105,988,647,454.02; ratio 2.19. December federal row 10,303,647,189.66 + 467,732,060.49 + 285,331,768.33 + 6,292,605,109.92 = 17,349,316,128.40 (table prints 17,349,316,128.41); audited 17,349,316,128.40. August 9,462,957,112.46 + 301,312,821.60 (exchange gain) + 449,849,528.44 + 270,395,167.40 + 7,416,851,087.25 = 17,901,365,717.15; audited 17,901,365,717.15. Audited total minus federal total gross amount, by month: January 0.00, February -1,553,954,585.34, March -1,485,680,074.08, April +0.01, May +108.64 (EMTL 469,079,872.24 audited against 469,079,763.60 federal), June 0.00, July -834,651,727.01, August 0.00, September +0.01, October 0.00, November 0.00, December -0.01. Federal total less VAT: February 15,818,665,286.22 - 8,569,426,721.90 = 7,249,238,564.32 (audited 14,264,710,700.88); March 15,019,565,868.81 - 6,998,966,998.25 = 8,020,598,870.56 (audited 13,533,885,794.73); July 16,373,966,217.61 - 7,366,781,905.45 = 9,007,184,312.16 (audited 15,539,314,490.60). The twelve audited monthly VAT figures equal the federal gross VAT column in every month; total 92,917,444,389.86. EMTL in the nine matching months 385,453,525.09 + 301,088,658.20 + 469,079,872.24 + 333,367,366.91 + 449,849,528.44 + 383,228,725.76 + 599,162,506.04 + 563,701,657.51 + 467,732,060.49 = 3,952,663,900.68. Other-receipts overlaps 2,899,766,655.49 + 4,811,784,669.73 + 592,923,354.31 + 563,928,204.12 = 8,868,402,883.65. Budget report 91,866,890,833.37 + 92,917,444,389.36 + 103,356,788,282.83 = 288,141,123,505.56; 91,866,890,833.37 - 89,391,435,885.28 = 2,475,454,948.09. 362,566,406,977.20 - 288,141,123,505.56 = 74,425,283,471.64; 362,566,406,977.20 - 92,917,444,389.86 = 269,648,962,587.34; 269,648,962,587.34 - 288,141,123,505.56 = -18,492,160,918.22. 362,566,406,977 / 432,350,910,704 = 83.9 per cent; 432,350,910,704 - 397,350,910,704.38 = 34,999,999,999.62. Cash flow 561,044,916,367 - 177,813,562,022 = 383,231,354,345 (printed 383,231,354,344); 383,231,354,344 - 451,119,440,555 + 89,380,413,196 = 21,492,326,985; 54,603,342,532 + 21,492,326,985 = 76,095,669,517. Capital 451,119,440,555 - 350,917,003,510.60 = 100,202,437,044.40. Debt 99,843,580,316.93 + 1,081,734,816.57 + 41,747,161,012.40 = 142,672,476,145.90 (DMO 142,672,476,145.90); 201,775,673,446.76 / 140,585,037.65 = 1,435.26. Opening balance 541,808,346,798.97 - 514,300,256,946.85 = 27,508,089,852.12 (budget 27,508,089,852.13); 76,095,669,517 - 75,876,574,214.16 = 219,095,302.84.
What this does not establish
Where in the cash-flow statement the counterpart of the duplicated VAT sits, given that the statement still reconciles to the N76,095,669,517 closing cash; the N100.20bn gap in capital spending between the accounts and the budget report is noted but not shown to be connected. Why the audited monthly totals for February, March and July are N1.55bn, N1.49bn and N0.83bn below the federal total gross amount. Whether the four entries in the other-receipts list that match amounts already inside the monthly totals are the same payments recorded twice. How the two documents' other FAAC receipts (N103.36bn in the budget report; N10.60bn and N63.67bn in the accounts) reconcile, and why their FAAC budgets differ by N35bn. Why the State Auditor-General's opinion and report do not mention the VAT line. The documents show a presentation and counting error in the accounts; they do not show that any money is missing, and nothing in them suggests wrongdoing by anyone. The Niger State Accountant-General and State Auditor-General were not asked for comment before publication.
What we did ourselves
Downloaded the 2025 audited accounts and the fourth-quarter 2025, second-quarter 2026 and third-quarter 2026 budget reports from the Niger Open Government Portal, and all twelve 2025 FAAC disbursement reports from the federal Accountant-General's website. Extracted Niger's row from each federal Table III and set it against the accounts' monthly statutory-allocation, VAT and EMTL schedules month by month, which showed that the accounts' statutory totals equal the federal total gross amount including VAT, and that Note 1 adds VAT a second time. Re-added Note 1, the budget report's FAAC lines and the cash-flow statement, and checked the accounts' debt notes against the DMO's state tables for 31 December 2025.
Sources for this report
(A) Niger State Government, Audited Financial Statements for the year ended 31 December 2025, Note 1 (p.36) and supplementary notes on the government share of FAAC and VAT (pp.93 to 95); Office of the Accountant-General of the Federation, FAAC disbursement reports January to December 2025, Table III, Niger row; Niger State Budget Performance Report, fourth quarter 2025, Table 3 (p.10).
- Niger State 2025 Audited Financial Statements (164 pages) · Niger State Government (Accountant-General; State Auditor-General) · 30 July 2026
- Niger State Budget Performance Report, Fourth Quarter 2025 · Niger State Government · January 2026
- Niger State Budget Performance Report, Second Quarter 2026 · Niger State Government · July 2026
- Niger State Budget Performance Report, Third Quarter 2026 · Niger State Government · 30 October 2026
- FAAC Disbursement January 2025 (Table III) · Office of the Accountant-General of the Federation · January 2025
- FAAC Disbursement February 2025 (Table III) · Office of the Accountant-General of the Federation · February 2025
- FAAC Disbursement March 2025 (Table III) · Office of the Accountant-General of the Federation · March 2025
- FAAC Disbursement April 2025 (Table III) · Office of the Accountant-General of the Federation · April 2025
- FAAC Disbursement May 2025 (Table III) · Office of the Accountant-General of the Federation · May 2025
- FAAC Disbursement June 2025 (Table III) · Office of the Accountant-General of the Federation · June 2025
- FAAC Disbursement July 2025 (Table III) · Office of the Accountant-General of the Federation · July 2025
- FAAC Disbursement August 2025 (Table III) · Office of the Accountant-General of the Federation · August 2025
- FAAC Disbursement September 2025 (Table III) · Office of the Accountant-General of the Federation · September 2025
- FAAC Disbursement October 2025 (Table III) · Office of the Accountant-General of the Federation · October 2025
- FAAC Disbursement November 2025 (Table III) · Office of the Accountant-General of the Federation · November 2025
- FAAC Disbursement December 2025 (Table III) · Office of the Accountant-General of the Federation · December 2025
- States and FCT Domestic Debt Stock as at December 31, 2025 · Debt Management Office · 2026
- States, FCT and Federal Government's External Debt Stock as at December 31, 2025 · Debt Management Office · 2026
- File:Minna.photowalk Tunga Roundabout.jpg · Wikimedia Commons · 8 November 2021
Confidence: high. This is our own assessment of whether the event occurred as described, separate from the grade, which describes what kind of thing the claim rests on.
Not obtained: where the underlying document is named above but not linked, we did not hold a copy at the time of publication. We purchase nothing and request nothing in our own name.
Corrections
None on this report. If you find an error, it will be published here, at the same length, with the date it was found, and the original wording will remain visible above it.
Dr VeroInvestigations editor, Vero Record
Reads the Nigerian public record that others leave unread: budgets, audit reports, court files and registers. Every claim on this page carries the grade of the document behind it, and the report says what that document does not establish.
All 157 reportsHow we grade evidenceAdd Vero Record as a preferred source on Google