Cross River's published 2025 audit stops in the middle of a sentence on page 65. Its certificate covers the accounts to page 80
The Auditor-General certifies that the consolidated financial statements are reproduced in his report from page 22 to page 80, and gives a special opinion on material he describes as being on page 81. The published document ends at printed page 65, part-way through note 17, on the words Mini Tractors Held for Distribution. Notes 18 to 33 are certified and absent, including the note that would explain the state's N9.35 trillion asset recognition.
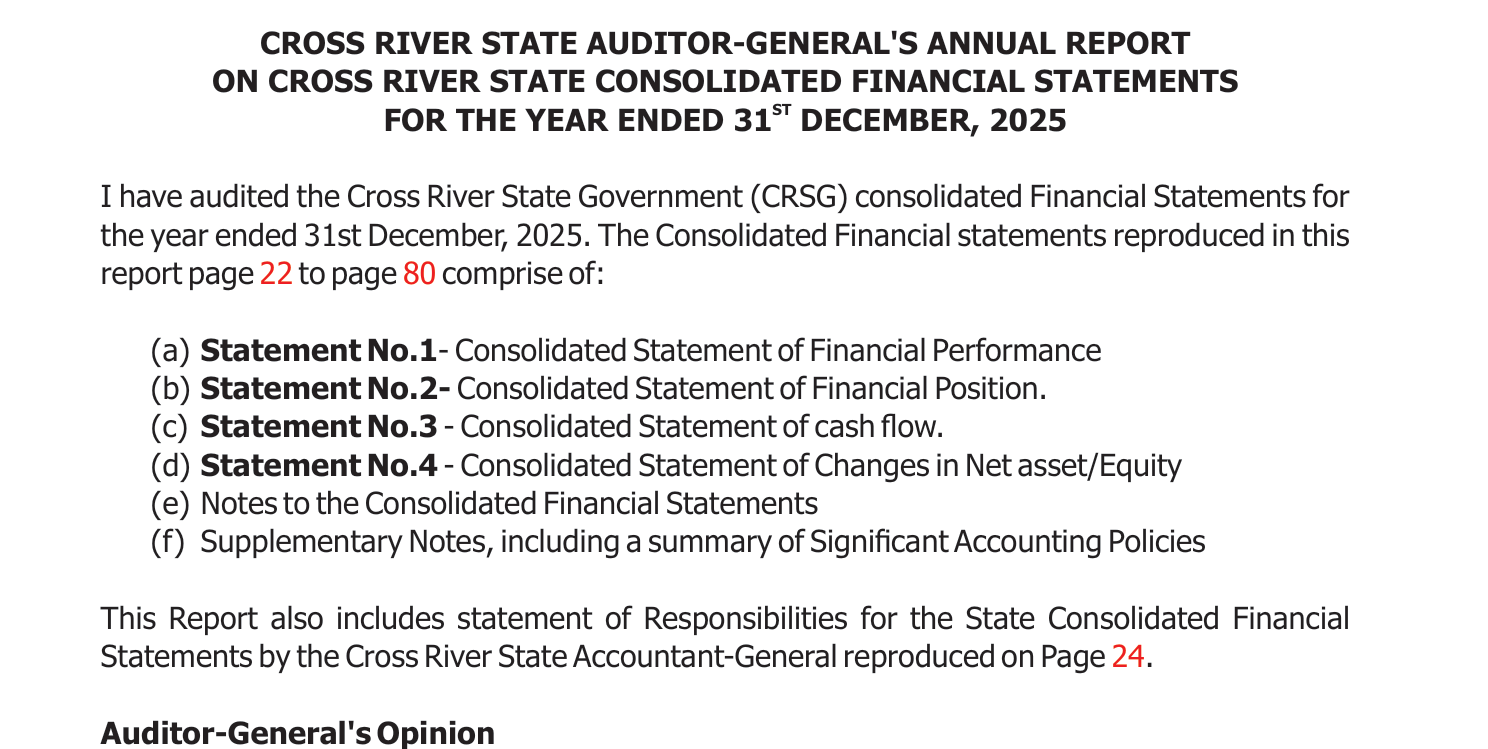
The certificate is on printed page 2. I have audited the Cross River State Government consolidated Financial Statements for the year ended 31st December, 2025, it reads. The Consolidated Financial statements reproduced in this report page 22 to page 80 comprise of, and then it lists them: five numbered statements, the notes to the consolidated financial statements, and supplementary notes including a summary of significant accounting policies.
On printed page 4, the Special Opinion adds a further reference. In my opinion, SPL Note 2 S/N 3 and note 33 presents fairly, in all material respect, the expenditures incurred and funds received against the programmes by the State for the year ended 31st December, 2025 in accordance with IPSAS as described in page 81.
The table of contents, printed page iii, is consistent with that: notes to the financial statements at 44, supplementary notes at 75.
The document we downloaded from the Auditor-General's own site has 68 pages. Its last printed page is 65. It ends in the middle of note 17, Inventories, after an entry reading Mini Tractors Held for Distribution and a code. There is no page 66. There is no page 81.
What is missing is not marginal. Notes 18 to 33 include note 22, property plant and equipment, the line that carries N14,858,069,984 thousand. Note 25, fair value through net assets and equity, which is where the state's carrying values for Tinapa sit. Notes 26 to 28, current liabilities. Note 30, financial liabilities and debt. And note 33, which is the note the Special Opinion is given on.
The one note that does appear out of sequence is note 34, printed beneath the Statement of Changes in Net Assets at page 42, which is where the N9,354,491,048,000 legacy asset recognition is explained. The note that quantifies it is there. The notes that would disaggregate it are not.
The comparison with the previous year is direct. The 2024 report reproduces notes 1 to 32 plus two supplementary notes, running to printed page 82.
We are careful about what follows from this. A truncated published PDF is not the same thing as a truncated report. The pages may exist, may have been printed, and may simply have been lost when the file was assembled or uploaded. That is the likeliest explanation and it would be an administrative failure rather than a substantive one.
But the consequence for a reader is the same either way. The audit certificate on Cross River's 2025 accounts certifies material that the published document does not contain, and the disclosure explaining the largest single entry in those accounts is not available to anyone reading the report the state put out.
What this rests on
Both reports were downloaded from the Office of the Auditor-General and read by Vero. The certificate pages are scanned images and were rendered and read directly.
What this does not establish
It does not establish that pages 66 to 81 were never written, or that anything was deliberately withheld. A file can be truncated in production or upload. It does not establish that the missing notes would show anything adverse. We have not put the question to the Auditor-General, and his answer belongs in any account of this.
What we did ourselves
We read the certificate against the document it certifies, and identified precisely which notes are covered by the opinion but absent from the publication, including the one the Special Opinion is expressly given on.
Sources for this report
(A) Cross River State 2025 Annual Report and Accounts, Office of the Auditor-General, 68 PDF pages, last printed page 65: audit certificate at printed p.2 stating the statements are reproduced 'page 22 to page 80'; Special Opinion at printed p.4 referring to material 'as described in page 81'; table of contents at printed p.iii listing notes at 44 and supplementary notes at 75; document ends mid-note 17 at printed p.65. Compared against the 2024 report, which reproduces notes 1-32 and supplementary notes to printed p.82.
Confidence: high. This is our own assessment of whether the event occurred as described, separate from the grade, which describes what kind of thing the claim rests on.
Not obtained: where the underlying document is named above but not linked, we did not hold a copy at the time of publication. We purchase nothing and request nothing in our own name.
Corrections
None on this report. If you find an error, it will be published here, at the same length, with the date it was found, and the original wording will remain visible above it.