Cross River added N9.35 trillion to its balance sheet on a valuation it performed itself, and its Auditor-General signed a clean opinion without mentioning it
The state's 2025 audited accounts recognise N9,354,491,048,000 of previously unrecognised legacy assets, valued using what the note calls in-house technical expertise, with no depreciation charged. The state's entire expenditure that year was about N205bn. The Auditor-General certified a true and fair view and raised no observation on it.
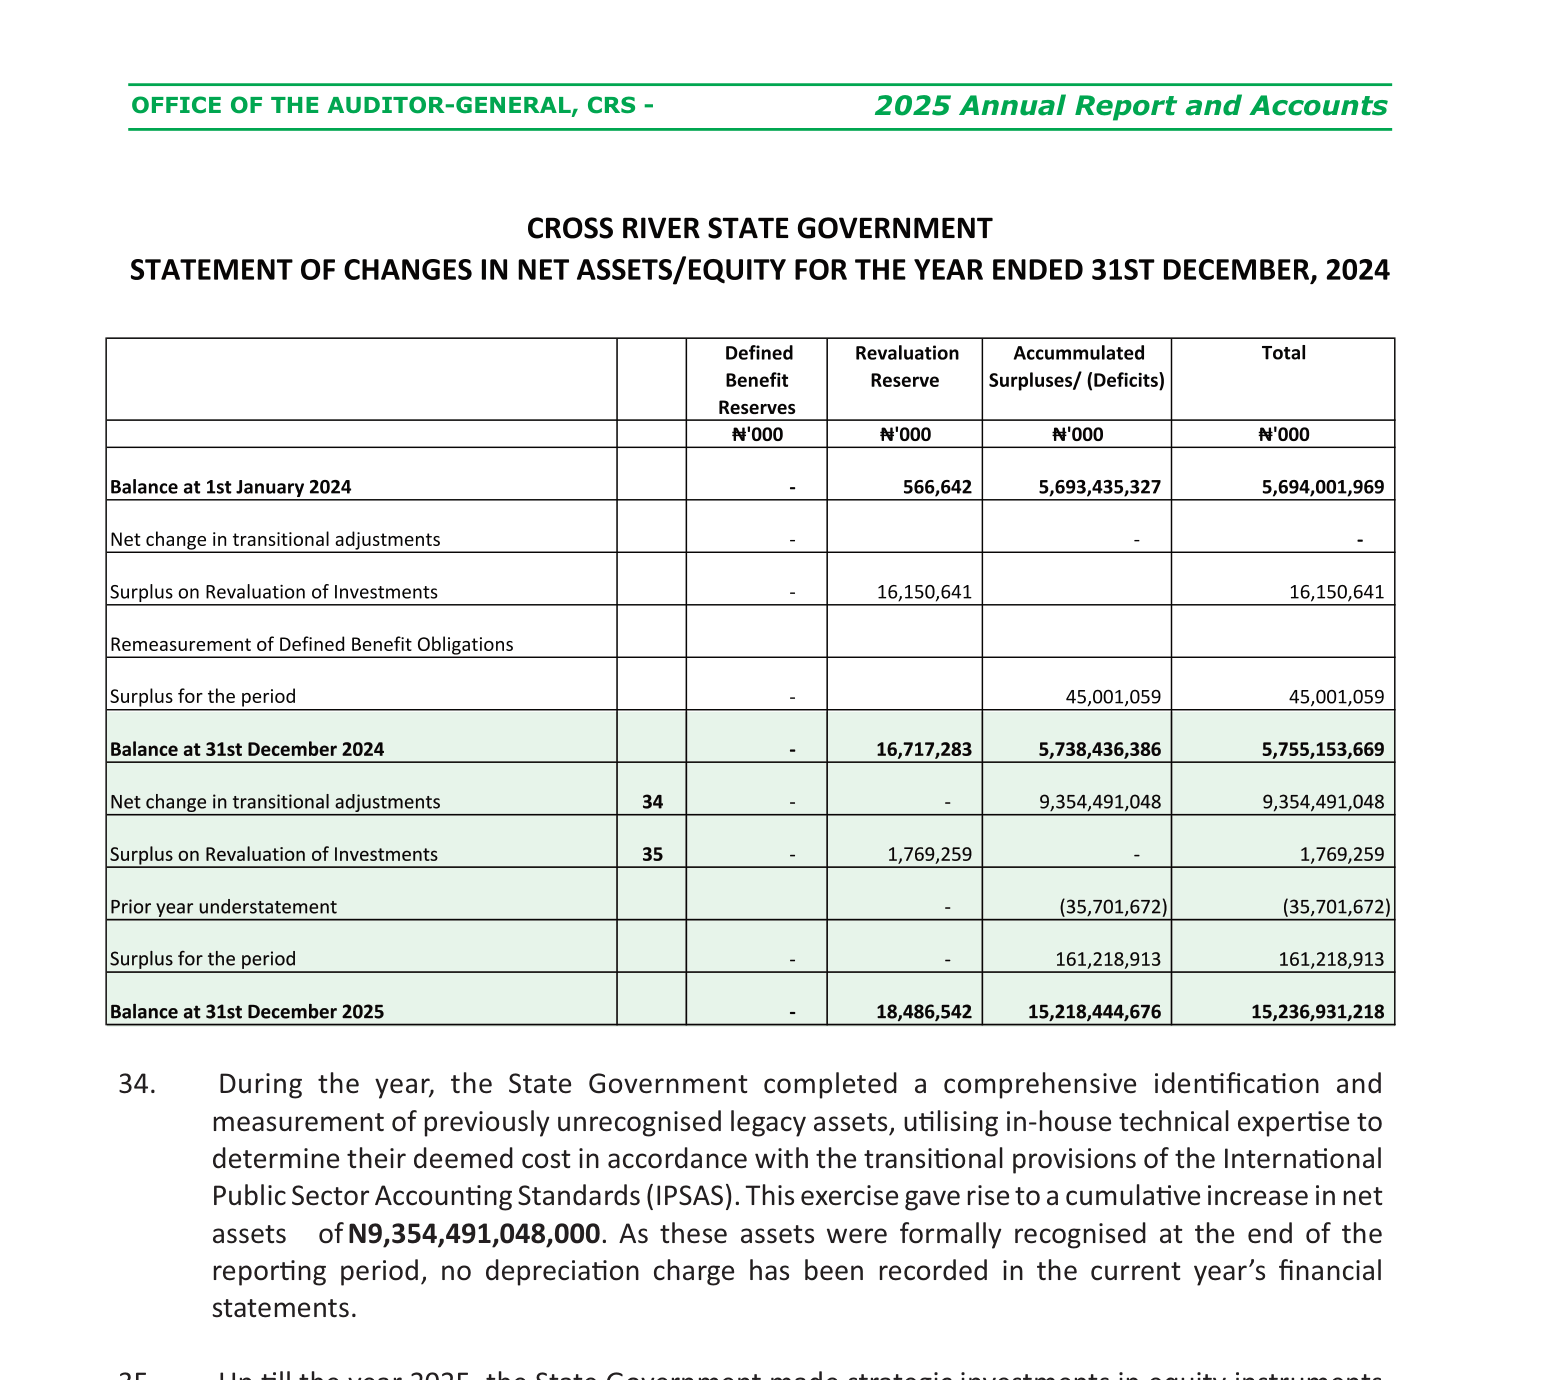
Cross River State's Statement of Changes in Net Assets and Equity, in its 2025 annual report and accounts, is set out in thousands of naira. The closing balance for 2024 is 5,755,153,669. The closing balance for 2025 is 15,236,931,218. The state's net worth multiplied by 2.65 in a single year.
One line produces almost all of it. Against note 34, the row reads Net change in transitional adjustments, 9,354,491,048.
Note 34, printed immediately beneath the statement, explains it in full: during the year the State Government completed a comprehensive identification and measurement of previously unrecognised legacy assets, utilising in-house technical expertise to determine their deemed cost in accordance with the transitional provisions of the International Public Sector Accounting Standards. The exercise gave rise to a cumulative increase in net assets of N9,354,491,048,000. And then, in the same note: as these assets were formally recognised at the end of the reporting period, no depreciation charge has been recorded in the current year's financial statements.
Three things in that sentence are worth separating. The valuation was performed by the state on its own assets. No external valuer is named anywhere in the report. And no depreciation is charged, so the figure enters the accounts at full value and carries no annual cost.
The scale only becomes clear next to the state's ordinary numbers, which are in the same report. Total 2025 expenditure: N205,134,423,000. Total 2025 revenue: N381,861,530,000. Net cash used in investing activities across the whole year: N195,865,808,000. Cross River added to its balance sheet, in one accounting exercise, roughly forty-five times what it spent in the year.
Property, plant and equipment moves accordingly, from 5,376,901,223 to 14,858,069,984 in thousands, and total assets from 6,284,434,099 to 15,791,737,345.
The Auditor-General's certificate on this report is unqualified. In his opinion, the financial statements show a true and fair view in all material respects. His Detailed Findings and Recommendations section, which runs to nine printed pages and does not shy from criticism elsewhere in the same document, contains no observation on the N9.35 trillion.
Its only appearance in his narrative gets it wrong. Under the heading Non-Current Assets, he records the increase of N9,551,615,787,000 and attributes it to investment in intangible assets, property plant and equipment, biological assets, investment property and gains from fair value. That is a description of money spent. In the same year, by the same report, the state's total investing cash outflow was N195.87bn and its entire expenditure was N205.13bn. Nothing on the scale of N9.55 trillion was bought.
Two further details are visible on the page. A line reading Prior year understatement (35,701,672) puts a N35.7bn correction to earlier years through the 2025 movement rather than restating the 2024 comparatives. And the statement's own heading says for the year ended 31st December, 2024, while the table it heads runs to 31 December 2025.
This does not establish that the assets are fictitious or the valuations wrong. IPSAS transitional provisions genuinely do permit a government adopting the standard to recognise previously unrecorded assets at deemed cost, and a state that has never valued its schools, roads and land would be expected to book a very large number when it finally does. That is the ordinary explanation and it may be the whole of it.
What the record establishes is the scale, the absence of any named external valuer, the explicit absence of depreciation, and the fact that the officer whose job is to examine these accounts certified them without comment and, where he did describe the movement, described it as something the cash flow statement in the same report shows it was not.
What this rests on
The report was opened and read by Vero. The financial statements in this document are scanned images without a text layer, so the pages were rendered and the figures read off them directly. All amounts are as printed, in thousands of naira except where note 34 states the sum in full.
What this does not establish
It does not establish that the assets do not exist, that the valuations are wrong, or that anyone benefited. IPSAS transitional provisions permit deemed-cost recognition of previously unrecognised assets, and a first valuation of a state's accumulated property would legitimately be large. It does not establish why the Auditor-General did not comment, and it attributes no impropriety to him or to any official. No court has found any wrongdoing here.
What we did ourselves
We set the transitional adjustment against the state's own expenditure, revenue and investing cash flow from the same report, which is what turns a large accounting entry into a measurable one, and we read the Auditor-General's narrative on non-current assets against the cash flow statement he certified on the same day.
Sources for this report
(A) Cross River State 2025 Annual Report and Accounts, Office of the Auditor-General: Statement of Changes in Net Assets/Equity and note 34 (printed p.42) recording a transitional adjustment of 9,354,491,048 in N'000 and a cumulative increase of N9,354,491,048,000 with no depreciation charged; Statement No. 2 (printed p.37) PPE 14,858,069,984 against 5,376,901,223 and total assets 15,791,737,345 against 6,284,434,099; Statement No. 3 (printed p.39) net cash used in investing activities 195,865,808; expenditure and revenue at printed p.7; unqualified audit certificate at printed pp.2-4; narrative on non-current assets at printed p.7.
Confidence: high. This is our own assessment of whether the event occurred as described, separate from the grade, which describes what kind of thing the claim rests on.
Not obtained: where the underlying document is named above but not linked, we did not hold a copy at the time of publication. We purchase nothing and request nothing in our own name.
Corrections
None on this report. If you find an error, it will be published here, at the same length, with the date it was found, and the original wording will remain visible above it.